
Blogs
Aramid Paper Market: Why 6.1% CAGR and Asia Pacific’s Growth Reshape 2032
By pmarketresearch, 2026-09-21
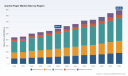
Aramid Paper Market: Strategic Trends and Commercial Opportunities Through 2032
The global aramid paper sector has entered a phase of measured expansion, driven by the material’s irreplaceable role in high-temperature insulation, fire safety, and lightweight structural reinforcement. Valued at approximately USD 587.6 million in 2025, the market is projected to grow at a compound annual growth rate of 6.1% through 2032, reaching an estimated USD 892.4 million. This trajectory reflects a broader industrial shift toward materials that balance thermal stability, dielectric strength, and mechanical durability. Historical growth from 2020 to 2025 has been steady, with annual revenue climbing steadily as electrical grid modernization, aerospace consolidation, and industrial automation have absorbed incremental volume. Yet the path ahead is not linear. Supply chain volatility, evolving regulatory expectations, and shifting competitive dynamics are reshaping how value is created and captured in this niche but strategically critical segment.
For executives and investors tracking high-performance materials, the aramid paper market offers a compelling case study in how specialized polymers navigate industrial cycles. The sector’s resilience stems from its integration into mission-critical applications where substitution is costly and downtime is unacceptable. At the same time, manufacturers and buyers must navigate a landscape where raw material pricing, compliance obligations, and geographic trade flows are increasingly interconnected. The following analysis examines the forces shaping the market, the strategies of leading players, and the strategic decisions that will determine competitive advantage over the next three to five years.
Market Landscape and Core Challenges
The aramid paper market operates within a highly concentrated environment, with the top three firms accounting for over three-quarters of global revenue and the top five collectively commanding more than four-fifths of supply. This concentration reflects the capital intensity of fiber-to-paper conversion, the technical expertise required for grade optimization, and the long qualification cycles inherent in aerospace, electrical, and transportation applications. While consolidation has delivered scale efficiencies and consistent quality control, it also creates structural dependencies that buyers and suppliers must manage carefully.
Key Challenges Shaping the Sector
Three interlocking challenges are redefining how the market evolves. First, feedstock volatility has introduced unpredictability into cost structures. Para-aramid paper production relies heavily on para-phenylenediamine and terephthaloyl chloride, and price movements in these inputs directly affect manufacturing margins and downstream pricing power. Recent quarterly increases of approximately six percent in Chinese spot markets illustrate how supply constraints and aerospace-driven demand can compress margins when producers lack hedging mechanisms or long-term contractual buffers.
Second, regulatory complexity is accelerating. Europe’s Ecodesign for Sustainable Products Regulation, which has been effective since mid-2024, requires digital product passports for aramid paper by 2030 to support traceability and circularity claims. Simultaneously, stricter chemical registration and restriction frameworks are influencing formulation decisions, particularly for meta-aramid grades used in electrical insulation. Fire safety standards across multiple jurisdictions, including UL 94, NFPA 701, and EN 45545-2, continue to mandate rigorous compliance testing for applications in electrical systems and transportation. These requirements increase time-to-market for new grades and raise the barrier for smaller producers who lack robust documentation and testing infrastructure.
Third, trade policy is reshaping regional supply flows. Cumulative tariffs on certain meta-aramid insulation imports have reached levels that alter the economics of cross-border sourcing for North American electrical and aerospace sectors. These measures introduce cost premiums that ripple through procurement decisions, encouraging regionalization, inventory buffering, and alternative supplier qualification. For buyers, the challenge is balancing cost efficiency against supply continuity; for producers, the opportunity lies in localized capacity, differentiated service, and compliance-ready product architectures.
These challenges do not signal instability; rather, they highlight a maturing market where value is increasingly tied to reliability, compliance readiness, and supply chain intelligence. Companies that treat regulation and trade conditions as strategic variables rather than administrative hurdles are better positioned to protect margins and deepen customer relationships.
PW Consulting
Key Drivers of Market Evolution
Technological Innovation and Grade Optimization
Advancements in thermal resistance, dielectric performance, and mechanical consistency are expanding the addressable use cases for aramid paper. Du Pont’s recent portfolio updates, including improved thermal resistance grades for industrial and aerospace applications, demonstrate how incremental material engineering can unlock qualification in higher-temperature environments and more demanding insulation architectures. In parallel, Teijin Aramid’s digital product passport-aligned offerings show how compliance and traceability are becoming embedded into product design rather than treated as after-the-market add-ons.
For manufacturers, the strategic implication is clear: innovation cycles are shortening in areas where performance differentiation directly influences specification decisions. Investing in grade development, process control, and application-specific testing can convert technical advantages into commercial lock-in. For buyers, the opportunity lies in collaborating with suppliers on qualification roadmaps that anticipate future thermal, electrical, and fire-safety requirements before they become constraint-driven mandates.
Policy and Regulatory Environment
Regulatory momentum is a defining force in the aramid paper market. The digital product passport requirement signals a broader push toward supply chain transparency and circular economy accountability. Beyond Europe, fire safety and chemical compliance standards continue to influence product design and approval timelines across electrical insulation and transportation end markets. These frameworks reward producers with robust documentation, consistent batch quality, and clear material traceability, while increasing the cost of non-compliance for any participant that treats certification as a tactical checkpoint.
The commercial impact is twofold. First, compliance capability is becoming a competitive filter, particularly in segments where safety certification and material provenance are inseparable from procurement decisions. Second, regulatory alignment creates opportunities for value-added services such as lifecycle documentation, responsible sourcing verification, and end-of-use guidance. Organizations that integrate compliance into their product strategy can reduce friction in specification approvals and strengthen their position in regulated markets.
Demand-Side Shifts in Electrical, Aerospace, and Industrial Sectors
Demand growth is being shaped by three overlapping trends. Electrical insulation remains the largest application segment, supported by grid modernization, transformer upgrades, and the expansion of high-voltage infrastructure. Aerospace and defense applications continue to absorb aramid paper where weight reduction, thermal stability, and fire resistance must coexist, particularly in composite reinforcement and insulation systems. Meanwhile, industrial and automotive insulation needs are evolving as electrification and automated manufacturing increase the prevalence of high-temperature electrical and mechanical environments.
These demand shifts are not uniform across regions or customer segments. In mature markets, replacement and upgrade cycles drive volume, while in faster-industrializing regions, new infrastructure build-out and localized manufacturing expansion create incremental demand. The commercial takeaway is that aramid paper is increasingly tied to system-level modernization rather than commodity substitution. Buyers evaluating total cost of ownership, reliability, and compliance continuity are more likely to prioritize proven performance over short-term price optimization.
Supply Chain and Cost Structure Dynamics
The cost structure of aramid paper is sensitive to feedstock pricing, regional production footprints, and logistics complexity. Para-aramid feedstocks remain the primary cost driver, and recent spot price movements highlight how supply constraints and application-specific demand can interact to create quarterly volatility. At the same time, the presence of regional producers serving Asia-Pacific and Southeast Asian markets has diversified supply options, though often with trade-offs in scale, certification breadth, or grade consistency.
For procurement strategies, this environment rewards multi-source planning and supplier development. Companies that maintain visibility into feedstock trends, qualify alternative grades, and build relationships with converters offering slitting, die-cutting, and custom lamination can reduce exposure to single-point disruptions. For producers, cost competitiveness increasingly depends on process efficiency, grade yield, and service breadth rather than volume alone. In a concentrated market, the ability to deliver consistent quality with flexible formats and compliant documentation is a meaningful differentiator.
Competitive Landscape and Leading Strategies
The competitive structure of the aramid paper market reflects a blend of established multinational producers, regionally focused manufacturers, and specialized converters. E. I. du Pont de Nemours and Company maintains a leading position through its Nomex and Kevlar grades, with a strong footprint in electrical insulation, aerospace composites, and high-temperature applications. Teijin Aramid complements this profile with an integrated fiber-to-paper supply chain and a portfolio encompassing Technora and Twaron grades, serving aerospace, automotive, and electrical insulation markets with an emphasis on end-to-end control. Yantai Tayho Advanced Materials has emerged as a significant producer of meta-aramid paper for electrical insulation and transformer applications, leveraging expanded capacity to serve Asia-Pacific demand. SRO Aramid and Ganzhou Longpont Material Technology contribute additional capacity in the electrical insulation segment, often with a focus on cost-competitive supply to Chinese and Southeast Asian markets. Kolon Industries supplies para-aramid and meta-aramid variants for industrial and automotive insulation applications, while Tokushu Tokai Paper continues to promote its TT-TOKRON grade in transformer and motor insulation markets following its initial launch. Yantai Metastar Special Paper adds further regional supply through its Metastar-branded meta-aramid paper for electrical insulation and transformer use. Pronat Industries rounds out the landscape as a converter and distributor, offering slitting, die-cutting, and custom lamination services that extend the reach of branded aramid paper into tailored formats.
Strategic Positioning and Differentiation
Leading players are differentiating along several axes. Multinational producers emphasize brand recognition, qualification depth, and global service networks, which reduce risk for OEMs and specifiers in aerospace and high-voltage electrical applications. Regional producers compete on capacity availability, localized service, and price positioning, often gaining traction where procurement teams prioritize responsiveness and regional supply continuity. Converters and distributors add value through format flexibility, custom processing, and inventory management, enabling end users to integrate aramid paper into mixed-material assemblies with less friction.
Aramid (Aramid Fiber) Market
A notable strategic shift is the embedding of compliance and traceability into product architecture. Teijin Aramid’s rollout of digital product passport-compliant products aligned with Europe’s Ecodesign for Sustainable Products Regulation illustrates how traceability is moving from a documentation exercise to a product feature. Similarly, Tokushu Tokai Paper’s continued promotion of TT-TOKRON in transformer and motor insulation markets reflects a strategy of sustained market adoption through application focus and specification reinforcement. For buyers, this means that supplier selection increasingly involves evaluating not only grade performance but also documentation readiness, regulatory alignment, and the ability to support lifecycle expectations.
Market Structure Evolution
The market is evolving along three concurrent directions. Consolidation among established producers continues to reinforce scale advantages and qualification moats, particularly in segments where certification cycles are long and switching costs are high. At the same time, regional capacity additions are expanding supply options in Asia-Pacific and adjacent markets, creating a more layered competitive environment where price, service, and compliance readiness interact differently by customer segment. New entrants and converters are also finding niches by offering tailored formats, value-added processing, and specialized documentation support, even as they operate within a market where core fiber supply and grade development remain concentrated.
For strategic planners, the practical implication is that the market is not simply becoming more crowded or more consolidated; it is becoming more segmented by capability. Suppliers that can demonstrate consistent performance, regional responsiveness, and regulatory alignment will capture share in specification-driven applications, while those that compete primarily on price will face pressure where qualification breadth and documentation quality matter. The winners are likely to be those that treat compliance, traceability, and service flexibility as part of the core product proposition.
Future Trends and Commercial Opportunities
Trend One: Compliance and Traceability as Default Requirements
The trajectory toward digital product passports, chemical compliance, and fire-safety certification is unlikely to reverse. By 2030, traceability and circularity documentation will be expected rather than optional in many European-facing supply chains, and similar expectations are likely to influence procurement decisions in other regions as standards propagate. This trend creates commercial opportunities for producers and converters that invest early in documentation infrastructure, responsible sourcing verification, and lifecycle support. For buyers, it enables faster specification approvals and clearer risk management in regulated applications. The risk lies in late movers facing compliance gaps that delay qualification or restrict market access, particularly in segments where safety and material provenance are tightly linked.
Trend Two: Regionalization and Supply Chain Buffering
Tariff effects, feedstock volatility, and the desire for supply continuity are encouraging regional sourcing strategies and inventory buffering. Over the next three to five years, procurement teams are likely to balance global scale with regional resilience, qualifying multiple suppliers and increasing the share of locally supported supply in critical applications. This trend benefits regional producers and converters that can offer responsive service, format flexibility, and localized technical support. It also creates opportunities for producers to differentiate through guaranteed lead times, transparent pricing mechanisms, and application-specific grade libraries. The uncertainty is whether regionalization will remain cost-neutral or impose premiums that reshape competitive positioning across segments.
Trend Three: Higher-Performance Grades in Electrical and Aerospace Applications
Continued investment in thermal resistance, dielectric strength, and mechanical consistency is expected to expand the use of aramid paper in higher-temperature and more demanding insulation architectures. Du Pont’s improved thermal resistance grades and broader application focus signal that performance upgrades can unlock new specification opportunities, especially where system designers must push thermal boundaries without compromising safety. For commercial teams, the opportunity is to align grade development with qualification roadmaps in electrical insulation and aerospace composite systems, reducing the time between material advancement and adoption. The risk is that performance gains must be matched by testing, documentation, and customer qualification capacity, otherwise technical advantages do not translate into commercial share.
Strategic Recommendations for Decision Makers
For Manufacturers and Suppliers
Invest in compliance-ready product architecture and documentation as a core capability rather than a peripheral function. Align grade development with the qualification needs of electrical insulation, aerospace, and industrial applications, and ensure that traceability, fire-safety certification, and chemical compliance are integrated into the product story. Strengthen regional service capability where tariff and feedstock dynamics make responsiveness a competitive lever. For converters, emphasize format flexibility, custom processing, and inventory support to capture value in segments where end users prioritize integration simplicity and supply predictability.
For Investors
Prioritize participants with durable qualification moats, traceable supply chains, and clear exposure to electrical insulation and aerospace demand. Evaluate cost structures with attention to feedstock exposure and regional pricing dynamics, and assess whether a company’s differentiation is sustainable beyond price competition. Opportunities are likely to accrue to firms that can combine scale with compliance readiness and that serve segments where switching costs and certification requirements limit substitution. Monitor regional capacity additions and converter networks, as these can create new value pools even within a concentrated market.
For Procurement and Engineering Leaders
Build multi-source strategies that balance global qualification depth with regional service responsiveness. Qualify alternative grades and formats early, and treat compliance documentation, traceability, and lead-time reliability as evaluation criteria alongside performance and price. In electrical insulation and transportation applications, align procurement decisions with anticipated regulatory and fire-safety requirements to reduce rework and qualification delays. Where possible, collaborate with suppliers on specification roadmaps that anticipate higher-temperature and higher-dielectric demands before they become constraint-driven.
Electrical Insulation Paper Market
Accessing Deeper Segment Intelligence
The aramid paper market is moving from a phase of steady expansion into a period where compliance, regional supply strategy, and grade performance will determine competitive outcomes. The forces shaping this transition are visible today in feedstock dynamics, regulatory timelines, tariff effects, and the evolving positioning of leading producers and converters. Decision makers who understand these interlocking dynamics can protect margins, reduce qualification friction, and position their organizations for the next cycle of specification growth.
For executives and investors who require deeper segment-level data, detailed application and regional breakdowns, and customized scenario analysis, a comprehensive research report is available that extends these insights with granular market sizing, competitive benchmarking, and tailored strategic recommendations. The full report provides the context needed to translate market-wide trends into operational and investment decisions across specific segments and geographies.
For detailed analysis of this topic, please visit the official page: Aramid Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Air Beds Market Hits $340M in 2025: 7.9% CAGR and Asia Pacific Reshaping Revenue by 2032
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Air Beds Market
Market Overview: Scale, Trajectory, and Structural Realities
The global air beds market has evolved from a niche hospitality and camping accessory into a diversified commercial category shaped by shifting sleep preferences, flexible accommodation models, and incremental engineering improvements. Between 2020 and 2025, the market expanded from roughly 230 million USD to 340 million USD, reflecting a compound annual growth rate of 7.9 percent over the broader forecast window through 2032. By the end of the projection period, revenue is expected to approach 575 million USD, indicating sustained demand expansion rather than a temporary post-pandemic rebound. This trajectory suggests that air beds are no longer treated as disposable substitutes but are increasingly evaluated against conventional foam, innerspring, and hybrid sleep surfaces on the basis of portability, space efficiency, and targeted comfort performance.
The composition of demand reveals a market in transition. Household applications continue to anchor the majority of revenue, driven by guest accommodation, apartment living, and multi-purpose room setups where floor space is at a premium. Commercial deployments represent a meaningful secondary channel, with hospitality operators, event organizers, and emergency housing providers leveraging air beds for rapid scalability and reconfiguration. The product mix remains bifurcated: one segment emphasizes consumer-grade mattresses designed for prolonged home or guest use, while the other focuses on traditional air beds optimized for temporary deployment, travel, and outdoor recreation. This divergence matters because each segment faces distinct performance expectations, margins, and replacement cycles.
Concentration levels underscore the strategic importance of brand position and distribution reach. A small group of established players controls a substantial share of revenue, particularly in the consumer category, where repeat purchases, retail visibility, and brand trust heavily influence category growth. At the same time, the market has not reached full consolidation, leaving room for specialized manufacturers, regional distributors, and performance-oriented entrants to carve out defensible niches. The reality on the ground is therefore one of measured expansion layered with structural friction: strong top-line growth coexists with pricing pressure, substitutability concerns, and uneven channel performance across segments.
PW Consulting
Key Challenges and Inflection Points
The most pressing challenge is the tension between convenience and long-term performance perception. Air beds have historically been associated with temporary use, and many buyers still hesitate to treat them as primary sleep surfaces. This perception cap limits penetration in households seeking durable, everyday comfort solutions. Overcoming it requires more than incremental softness improvements; it demands demonstrable durability, stable support under repeated inflation cycles, and clear differentiation from low-cost, short-lived alternatives that damage category credibility.
A second inflection point involves channel fragmentation and the shifting economics of trial and return. In online-first retail, buyers increasingly expect easy testing, clear product descriptions, and reasonable return policies. For bulky or inflatable products, logistics costs and return rates can erode margins quickly, especially when specifications are ambiguous or when products are positioned too close to conventional mattresses without clear justification. Companies that cannot align product messaging, packaging, and fulfillment with digital purchasing behavior risk losing share to brands that make the buying decision simpler and more predictable.
The third challenge is regulatory and sustainability scrutiny around materials and end-of-life handling. As consumer awareness of product composition grows, manufacturers face increased pressure to justify material choices, reduce environmental footprints, and avoid over-reliance on formulations that invite reputational or compliance risk. This is not yet a uniform market requirement, but it is becoming a differentiator in premium segments and in procurement environments where sustainability criteria influence vendor selection. Companies that address this proactively can use it as an entry point into higher-margin channels, while laggards may find themselves excluded from bids or retail listings that increasingly factor in material transparency.
Core Drivers Shaping Market Direction
Technological Advancements and Performance Engineering
The most tangible driver of category evolution is engineering progress in support stability, air retention, and integrated convenience features. Modern designs increasingly combine internal coil structures, layered fiber or fabric systems, and refined valve or pump mechanisms to address long-standing complaints about sagging, leakage, and uneven pressure distribution. These improvements matter because they shift the product narrative from temporary convenience to viable comfort support, especially for guest rooms, multi-use spaces, and short-term lodging. Pumping technology has also become more integrated and quieter, reducing friction in setup and improving usability for both consumer and commercial settings.
Several established manufacturers illustrate this trajectory. Intex Recreation Corp. has emphasized fiber-tech construction and high air retention in consumer-oriented lines, reinforcing the idea that air-based products can deliver more consistent comfort over repeated use. Coleman has focused on leak-resistant airbed cots and raised designs with coil support, targeting outdoor and guest applications where durability and quick deployment are critical. Sound Asleep Products has built its Dream Series around internal pump integration and eco-friendly PVC construction, reflecting a broader move toward convenience and material-conscious positioning. King Koil Airbeds has pursued a luxury-leaning angle with enhanced coil technology and built-in pumps for guest and home use, demonstrating how elevated support claims can support higher price points. These product directions are not isolated; together they signal a market that is rewarding precision, reliability, and clearer use-case positioning.
Policy, Regulation, and Procurement Standards
Policy and procurement environments are becoming more influential as buying decisions move beyond pure price comparison. In commercial and institutional settings, procurement teams increasingly evaluate durability, maintenance requirements, and material documentation alongside upfront cost. Where public or large-scale private buyers incorporate sustainability, safety, or vendor qualification criteria, air bed suppliers that can provide consistent specifications and reliable compliance narratives gain an advantage. This does not mean regulation is changing the market overnight, but it is raising the floor for what qualifies as an acceptable commercial product in certain channels.
At the same time, labeling and material disclosure expectations are gradually shaping consumer confidence. Buyers are more likely to engage with brands that communicate construction details clearly, especially when a product is positioned as suitable for longer-term guest or household use. This trend favors companies that invest in straightforward product storytelling and consistent quality control, while penalizing those that rely on vague comfort claims without supporting design or manufacturing discipline.
Hospital Beds Market
Demand-Side Shifts in Consumer and Commercial Behavior
Demand is increasingly shaped by space constraints, flexible living arrangements, and the normalization of temporary or multi-purpose furniture. In urban and rental-heavy housing markets, consumers value products that can be stored compactly, deployed quickly, and repurposed across guests, travel, or seasonal needs. This supports continued household demand, particularly where bedrooms are shared or where a secondary sleeping surface must be available on demand. At the same time, consumer expectations for comfort have risen, meaning that basic inflatable products face tougher competition from designs that approximate the feel of more traditional sleep surfaces.
On the commercial side, the relevance of air beds depends on operational flexibility. Hospitality operators, event providers, and overflow accommodation managers value products that can be installed rapidly, sanitized or replaced with minimal downtime, and adapted to varying occupancy patterns. This creates recurring demand in settings where speed and reconfigurability matter more than permanent bed infrastructure. Glamping and outdoor lodging concepts have also expanded the commercial-use conversation, with brands such as Zempire emphasizing durable bases and stretch fabrics for outdoor and renovated camping environments. Such use cases illustrate how commercial demand can stretch beyond traditional hospitality and into experience-led accommodation models.
Air Springs Market
Supply Chain and Cost Structure Dynamics
Cost structures remain sensitive to materials, manufacturing consistency, and outbound logistics. Inflationary pressure on components and freight has periodically squeezed margins, especially for lower-priced products where cost differentiation is already narrow. In response, manufacturers have leaned more heavily on design efficiency, localized product variation, and packaging optimization to protect viability without undermining perceived value. Supply chain resilience has also become a strategic consideration, as disruptions can quickly affect retail availability and commercial replenishment cycles.
For both consumer and commercial players, the practical implication is that total cost of ownership is increasingly important. A cheaper unit with higher failure or replacement frequency may be less attractive than a slightly more expensive option with better durability and lower service burden. This shifts attention toward engineering consistency, quality assurance, and after-sale support, especially for commercial buyers managing multiple units across locations.
Competitive Landscape and Strategic Positioning
The market is anchored by a set of recognizable manufacturers with distinct positioning. Intex Recreation Corp. maintains a strong consumer-facing presence through product lines that emphasize comfort features and practical inflation performance, supported by broad retail familiarity. Coleman leverages its outdoor and seasonal brand equity to compete in recreational and guest-use segments, where leak resistance and straightforward setup are valuable selling points. Sound Asleep Products and King Koil Airbeds both pursue more comfort-oriented narratives, but with different emphases: one leans into integrated convenience and material-conscious construction, while the other targets a higher-end feel with enhanced coil support and built-in pumps for home and guest applications.
Beyond the consumer core, specialized players add differentiation through use-case focus. Zempire has positioned itself in glamping and outdoor applications with durable bases and stretch fabrics, an approach that aligns with experience-led lodging and camping demand. Pittman Outdoors has built relevance through vehicle-specific and truck bed air mattress solutions, an example of how niche adjacency can create defensible demand where general-purpose products are less optimized. Together, these companies illustrate that competitive advantage in this market is rarely about scale alone; it is often about how precisely a brand aligns product design, messaging, and distribution with a defined purchasing context.
Looking forward, the competitive landscape is likely to evolve along two parallel tracks. One track involves continued brand consolidation among broad consumer manufacturers that can compete across retail channels, manage product complexity, and sustain visibility in high-traffic categories. The other track favors targeted entrants and regional players that serve specific applications well enough to command better margins and stronger buyer loyalty. There is also room for private-label and procurement-oriented supply relationships, especially where commercial buyers prioritize specification consistency over brand recognition. The market is therefore unlikely to become monochromatic; instead, it will probably become more segmented, with winners defined by application fit as much as by product features.
Future Trends and Commercial Opportunities
Performance-Driven Premiumization in Household Use
One of the clearest medium-term trends is the gradual push toward more performance-oriented household products. As buyers become more comfortable evaluating air-based sleep surfaces for guest rooms and secondary bedrooms, manufacturers that can deliver stable support, low maintenance burden, and credible durability will have an opening to expand into higher-value positions. This trend creates opportunities for products that combine inflatable convenience with more conventional comfort expectations, particularly where integrated pumps, reinforced support structures, and clearer warranty or quality messaging reduce purchase risk. The commercial implication is straightforward: brands that can convincingly bridge the gap between temporary use and everyday comfort can capture willingness to pay that basic models cannot.
Expansion of Commercial, Experience-Led, and Flexible Accommodation Demand
Commercial demand is expected to remain important, but its composition may shift toward experience-led and flexible lodging contexts. Glamping, boutique outdoor retreats, event overflow, and short-term accommodation operators all value products that are quick to deploy, easy to maintain, and adaptable to changing occupancy. This creates opportunities for suppliers that can package products with operational reliability in mind, including consistent specifications, manageable storage profiles, and designs suited to repeated use. The broader opportunity lies in serving buyers who need sleep infrastructure that behaves more like flexible furniture than permanent fixtures, especially in settings where space and turnover are central constraints.
Material, Sustainability, and Procurement-Aligned Product Narratives
A third trend is the growing importance of material transparency and procurement-friendly positioning. As buying committees and retail gatekeepers pay closer attention to product composition, manufacturing consistency, and end-of-life considerations, companies that communicate clearly and maintain disciplined quality standards will be better placed to access premium retail listings and institutional buyers. This does not require dramatic reformulation across the board, but it does reward coherent product stories, controlled sourcing, and evidence-based claims. Businesses that treat sustainability and documentation as strategic assets rather than compliance overhead may find new access points in channels where trust and traceability increasingly influence purchasing decisions.
Risks and Uncertainties
Several uncertainties could shape how these trends play out. Consumer willingness to pay for upgraded air beds may stall if broader inflation or housing cost pressures tighten discretionary budgets, particularly in segments where air beds compete with lower-cost furniture alternatives. Substitution risk also remains relevant, as improved foam, hybrid, and modular sleep products continue to evolve and may capture buyers seeking permanent solutions. In commercial settings, demand can be sensitive to occupancy cycles, event activity, and procurement budget shifts, making revenue less predictable than in steady-state household use. Finally, any erosion in perceived product durability or inconsistent quality across batches could quickly weaken category confidence, especially in online channels where reviews and returns amplify negative experiences.
Strategic Implications for Decision-Makers
For Manufacturers
Product strategy should begin with use-case clarity rather than feature stacking. The most defensible positions emerge when a product is designed for a specific purchasing context, whether that is guest-room comfort, outdoor deployment, vehicle compatibility, or institutional repeated use. Once the application is defined, engineering priorities become easier to set: support stability, air retention, pump usability, material consistency, and packaging efficiency can all be tuned to the target buyer instead of diluted across competing demands. Manufacturing discipline matters as much as design ambition, because inconsistent quality in inflatable products quickly undermines trust and increases returns. Brands that invest in clear specifications, repeatable production, and reliable after-sale support will be better positioned to defend margins and expand into higher-value channels.
For Investors
Investment attention should focus on the segments where value creation is most sustainable. Broad consumer exposure can offer scale, but differentiation and channel fit often determine whether a player can maintain pricing power. Smaller, application-focused manufacturers may present more attractive operating leverage if they serve a defined niche with limited direct competition and clear procurement or retail gatekeeper alignment. Commercial-oriented supply relationships can also be attractive where recurring demand, specification reliability, and operational convenience create stickier customer relationships. At the same time, investors should monitor substitution risk and consumer sentiment, because the category's growth depends on continued acceptance of air-based sleep surfaces as more than temporary conveniences. Due diligence should therefore emphasize product consistency, channel economics, and the credibility of performance claims rather than headline category growth alone.
For Procurement and Commercial Buyers
Buying decisions should weigh total cost of ownership alongside upfront price. For household and guest applications, the practical question is whether a product will deliver consistent comfort and acceptable durability over its expected use life, not just whether it is inexpensive at checkout. For commercial deployments, the deciding factors often include storage efficiency, setup speed, sanitation or replacement feasibility, and the ability to standardize units across locations. Buyers benefit from demanding clearer product documentation, consistent specifications, and realistic warranty or replacement expectations, especially when purchasing at volume. Where sustainability or material transparency is relevant to internal procurement standards, it can be used as a screening criterion that narrows the field to suppliers with stronger operational discipline and more reliable documentation.
The air beds market is not expanding simply because consumers are buying more inflatable products; it is expanding because a growing set of households, lodging operators, and experience-driven businesses see air-based sleep surfaces as practical answers to space, flexibility, and deployment constraints. The next phase of value creation will belong to players who make those answers more credible, more durable, and more clearly aligned with real purchasing contexts. For decision-makers seeking to act on these dynamics with segment-level sizing, channel comparisons, and customized positioning guidance, the full research report is available for review.
For detailed analysis of this topic, please visit the official page: Air Beds Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Digital Valve Positioner Market: Why 5.2% CAGR and Industry Shifts Redefine Growth
By pmarketresearch, 2026-09-21
Navigating the Digital Valve Positioner Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for digital valve positioners has entered a phase of steady, structurally supported expansion. Valued at approximately $1.92 billion in 2025, the sector is projected to reach $2.73 billion by 2032, reflecting a compound annual growth rate of 5.2 percent over the forecast horizon. This trajectory is not merely a continuation of historical demand; it signals a fundamental shift in how industrial flow control systems are designed, operated, and maintained. As process industries prioritize precision, safety compliance, and operational visibility, digital valve positioners are transitioning from auxiliary instrumentation to core components of modern control architectures.
Understanding where this market is headed requires looking beyond aggregate figures. The growth is uneven across regions, unevenly distributed across application verticals, and increasingly shaped by certification requirements, protocol standardization, and the pace of industrial digitization. For executives and investors, the opportunity lies not in the market’s size alone, but in the alignment of technology roadmaps, regulatory timelines, and procurement cycles that will determine which players capture margin, which segments accelerate, and where integration risks emerge.
Market Snapshot and Structural Headwinds
The market’s baseline reflects a mature but evolving ecosystem. Over the past five years, revenue growth has been anchored by incremental upgrades in chemical processing, energy generation, and hydrocarbon handling facilities, where legacy analog and early electro-pneumatic systems are being replaced or retrofitted with digitally enabled controllers. The base-year valuation of $1.92 billion masks a more nuanced reality: adoption is concentrated in applications where failure penalties are high, regulatory scrutiny is intense, and downtime costs justify the premium for diagnostic and positioning accuracy.
Yet the sector faces several inflection points that will shape competitive outcomes over the next three to five years:
-
Certification bottlenecks and harmonization gaps. Hazardous-area approvals remain a gatekeeper for market entry and regional expansion. While leading controllers now carry ATEX, IECEx, CSA, and marine certifications, the fragmentation of testing requirements across jurisdictions increases time-to-market and compliance overhead for manufacturers seeking global scale.
-
Protocol proliferation versus interoperability demands. Facilities are deploying mixed communication stacks, from HART and Profibus PA to Foundation Fieldbus and emerging proprietary digital links. The absence of a single dominant protocol creates integration complexity for end users, while raising the engineering burden on OEMs that must maintain multi-protocol firmware and validation suites.
-
Legacy infrastructure and retrofit economics. A significant portion of installed valve assets were designed for pneumatic or basic electro-pneumatic actuation. The business case for retrofitting depends on site-specific downtime windows, spare-parts compatibility, and the ability to demonstrate measurable gains in positioning accuracy, leak reduction, or predictive maintenance payback.
Digital Pressure Gauges Market
Core Drivers Reshaping Demand and Competitive Logic
The market’s trajectory is being pulled by a combination of technological, regulatory, and demand-side forces. These drivers do not operate in isolation; they reinforce one another and create distinct value pools for suppliers that can sequence product development, certification, and service models effectively.
Piezo Positioners Market
Technology Innovation and the Diagnostic Premium
The most visible driver is the shift from positioning accuracy alone to holistic device intelligence. Contemporary controllers increasingly bundle on-board pressure sensing, closed-loop feedback, and real-time diagnostic outputs that enable condition monitoring without additional field instrumentation. This evolution is not cosmetic; it changes the economic calculus for plant operators. A positioner that can surface drift, hysteresis trends, or air supply anomalies reduces the need for manual rounds and unplanned shutdowns, while creating a clearer path to predictive maintenance programs.
Recent product activity illustrates this direction. In March 2025, Emerson introduced the Fisher FIELDVUE DVC7K digital valve controller engineered for on/off applications, unifying control behavior with position feedback in a single platform. A month later, the company published an updated instruction manual for the DVC7K-H variant, signaling sustained investment in documentation, field usability, and service clarity. These moves reflect a broader industry pattern: manufacturers are competing not only on hardware robustness, but on the transparency and reliability of diagnostic workflows, including software-linked insights that help operators interpret device health without specialized instrumentation expertise.
Regulatory Pressure and Safety-Critical Positioning
Regulatory and safety expectations are simultaneously a constraint and a demand catalyst. In hazardous environments, positioners must demonstrate robust performance under flameproof, intrinsic safety, and dust ignition conditions, while supporting functional safety targets where process risk warrants it. This has elevated the importance of certifications such as ATEX and IECEx, alongside region-specific approvals like CSA and marine certifications for offshore and marine installations.
For suppliers, certification depth has become a differentiator rather than a baseline. Devices that carry multiple hazardous-location approvals and are engineered to support higher safety integrity requirements unlock access to capital-intensive and tightly regulated segments. At the same time, the compliance burden favors organizations with established testing infrastructure and repeatable validation processes, creating a structural advantage for incumbents that can sustain certification portfolios across product families. This dynamic is visible across multiple offerings: Woodward’s DVP emphasizes ATEX, IECEx, CSA, and marine approvals for hazardous and marine use; Baker Hughes’ Masoneilan SVI3 is positioned as SIL3 capable with ATEX, IECEx, and US/Canada approvals for flameproof, intrinsic safety, and dust ignition proof environments; Flowserve’s PMV D3 carries ATEX and CSA/FM explosion-proof approvals for hazardous areas; and Emerson’s DVC7K integrates hazardous-area approvals with diagnostic software linkages. The pattern confirms that safety certification is now a core element of commercial positioning, not an afterthought.
Demand-Side Shifts: Reliability economics and operational visibility
On the demand side, the strongest pull comes from operators treating valve control as a reliability and energy-efficiency lever. In oil and gas, energy and power, and chemical processing, facilities are under pressure to reduce non-productive time, tighten emissions control, and improve throughput consistency. Digital positioners support these goals by improving control-loop stability, reducing calibration drift, and enabling faster commissioning through clearer configuration and feedback.
Behavior is also changing at the procurement and engineering level. Projects are increasingly specifying devices that can interface cleanly with broader automation and asset-management environments, reducing the need for isolated point solutions. This preference rewards controllers that offer modular architectures, clear protocol support, and straightforward integration paths. At the same time, end users are more willing to accept a premium where the device can demonstrate measurable improvements in positioning repeatability, diagnostic coverage, or maintenance interval extension. The result is a demand environment that rewards practical reliability over marketing language, and that favors suppliers able to tie device capabilities to operational outcomes.
Supply Chain and Cost Structure Dynamics
Supply chain and cost considerations are exerting a more subtle but durable influence. Component availability, semiconductor sourcing, and the cost of certified enclosures and hazardous-area construction materials affect both pricing and lead times. Manufacturers that can secure stable input channels, design for manufacturability across variants, and avoid over-customization at the edge gain resilience in a market where project timing and spare-parts availability matter as much as unit price.
Cost structures are also being reshaped by the move toward smarter controllers that reduce downstream engineering and maintenance burden. When a positioner lowers field calibration frequency or simplifies protocol configuration, the total cost of ownership argument improves even if the upfront device price is higher. This dynamic is particularly important in retrofit projects, where installers must weigh integration effort against long-term operational savings. Suppliers that can articulate and substantiate these lifecycle benefits are better positioned to defend margins in segments where price competition remains intense.
PW Consulting Automotive & Machinery Research Center
Competitive Landscape and Strategic Positioning
The market remains moderately fragmented, with the top three players collectively accounting for roughly a quarter of revenue and the top five approaching a third. This concentration leaves meaningful room for regional specialists, application-focused suppliers, and new entrants that compete on specific technical or commercial dimensions rather than on total portfolio breadth.
Leading manufacturers are differentiating along several complementary axes:
-
Safety and certification breadth. Companies that maintain extensive hazardous-area approvals and functional safety capability secure advantage in oil and gas, energy, and chemical segments where risk exposure is high and specification cycles are rigorous.
-
Diagnostic depth and software integration. Controllers that pair field-level sensing with accessible diagnostic software create a more compelling operational story. The ability to translate device outputs into actionable insights—supported by clear documentation and field service alignment—increasingly separates premium offerings from commodity positioning products.
-
Protocol flexibility and modular design. In environments where automation stacks are heterogeneous, multi-protocol support and modular hardware architectures reduce integration friction. This is especially relevant for brownfield projects and multi-vendor sites that cannot standardize on a single communication layer.
-
Application-specific engineering. Some suppliers compete by tailoring devices to particular valve types or operating conditions. Offerings optimized for quarter-turn valves, high-speed precise control, or on/off applications can outperform generalist devices in targeted segments, even if they lack the broadest portfolio.
The competitive map is also evolving through productization and consolidation dynamics. Large industrial automation and valve specialists are strengthening their positions by unifying hardware, software, and service narratives, while mid-tier players are carving niches around ruggedness, rapid configuration, or specific certification footprints. New entrants can still succeed by focusing on underserved application sets, simplifying installation and commissioning, or offering attractive retrofit paths for legacy systems. However, the barrier is rising: certification maintenance, multi-protocol support, and field-service credibility now form a more demanding baseline than in the past.
Strategic Outlook: Three Trends Defining the Next Three to Five Years
Looking ahead, the market’s evolution will be shaped by the intersection of technology maturity, regulatory continuity, and procurement behavior. Three trends are likely to have outsized influence on opportunity and risk.
Trend One: Diagnostics and Connected Maintenance Move from Feature to Standard Expectation
As operators accumulate field evidence that device-level diagnostics reduce troubleshooting time and improve maintenance planning, digital positioners will face growing pressure to deliver more than precise positioning. Over the forecast period, the baseline expectation will likely shift toward clearer health indicators, easier integration with asset management workflows, and documentation that supports field service without specialized interpretation. The commercial opportunity lies with suppliers that can standardize diagnostic packages across product lines, maintain firmware consistency, and provide practical software tools that do not require extensive training to use effectively. The risk is that diagnostic claims outpace field validation; devices that promise insight but deliver noisy or ambiguous outputs can erode trust and slow repeat adoption.
Trend Two: Certification and Safety Integrity Remain Market Gatekeepers
Hazardous-area approvals and functional safety capability will continue to shape where and how quickly digital positioners can be deployed. Segments with stricter risk profiles and tighter regulatory oversight will reward suppliers with well-maintained certification portfolios and clear safety documentation. Over time, the market may see modest convergence in testing expectations, but regional variation is unlikely to disappear entirely. The strategic implication is twofold: manufacturers should treat certification as a long-term portfolio investment rather than a per-product event, and end users should evaluate approval coverage as a core element of specification, not a secondary checkbox. Uncertainty remains around the pace of harmonization and the cost of maintaining approvals across multiple jurisdictions, both of which can affect launch timing and margin planning.
Trend Three: Retrofit and Brownfield Modernization Will Drive a Meaningful Share of Demand
While greenfield projects contribute to growth, a substantial portion of future demand will come from upgrading existing control loops and replacing aging analog or early electro-pneumatic devices. Retrofit economics will hinge on installation simplicity, compatibility with existing actuators and air supplies, and the ability to demonstrate payback through fewer calibration events, improved loop stability, or reduced downtime. Suppliers that offer drop-in compatibility, clear migration guidance, and predictable commissioning steps will be better positioned to capture this segment. The risk is that retrofit projects stall when integration complexity or valve-body compatibility is underestimated, which can slow adoption even when the technology case is strong.
Implications and Actionable Takeaways
The digital valve positioner market is expanding in a way that rewards commercial discipline as much as technical competence. The following implications are most relevant for different stakeholder groups.
For manufacturers and product leaders, the priority is to build coherence across hardware, certification, and diagnostic software. A strong controller that lacks robust approval coverage or reliable field documentation will underperform in regulated segments. Conversely, a well-certified device with unclear diagnostic value may struggle to justify premium pricing. Sequencing roadmap decisions around modular design, multi-protocol support, and lifecycle service clarity offers a more durable competitive position than chasing isolated feature additions.
For investors and corporate development teams, the market’s moderate concentration and application-driven growth create opportunities in companies with strong safety certification footprints, clear retrofit value propositions, or differentiated diagnostic integration. The key diligence question is whether a supplier’s technical claims translate into measurable operational outcomes that customers can repeat across sites. Revenue potential should be evaluated alongside certification maintenance costs, protocol support demands, and the realism of field-service capacity, since these factors shape both margin and scalability.
For procurement and engineering decision-makers, specification should balance compliance, integration, and total cost of ownership. Devices with broad hazardous-area approvals and proven protocol compatibility reduce project risk, while clear diagnostic and feedback capabilities can improve maintenance planning and loop stability. Retrospective value is often realized when the selected controller aligns with the site’s existing automation context and spare-parts strategy, rather than when it is chosen solely on the basis of peak specifications. Evaluating field documentation, configuration simplicity, and support pathways alongside hardware features leads to more reliable project outcomes.
Closing Perspective
The digital valve positioner market is entering a period where growth is supported by reliability economics, safety-driven specification, and the gradual shift toward smarter field devices. The $1.92 billion base year and the 5.2 percent compound trajectory through 2032 describe the scale of the opportunity, but the real strategic value lies in how that growth is distributed across applications, certifications, and integration models. Suppliers and buyers alike will benefit from focusing on the operational realities that determine adoption: hazardous-area readiness, diagnostic usefulness, retrofit practicality, and the clarity of the path from device to decision. For organizations seeking deeper segmentation detail, regional demand patterns, and tailored action plans for specific product categories, broader research coverage is available to support more precise planning.
For detailed analysis of this topic, please visit the official page: Digital Valve Positioner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Calcium Aluminate Cement Market: How Asia Pacific’s 5.2% CAGR Trajectory and Refractory Demand Reshape the Sector
By pmarketresearch, 2026-09-21
Calcium Aluminate Cement Market: Strategic Trends and Commercial Opportunities in a High-Performance Materials Landscape
The Calcium Aluminate Cement (CAC) market has evolved from a niche binder solution into a strategically critical materials segment that underpins industrial durability, infrastructure resilience, and next-generation thermal applications. With global revenue expanding from approximately $1.28 billion in 2020 to $1.69 billion in 2025, and a projected trajectory to $2.38 billion by 2032 at a five-year compound annual growth rate of 5.2 percent, the sector demonstrates steady, demand-led expansion. Growth is not uniform across regions or use cases; rather, it reflects concentrated industrial adoption, shifting engineering requirements, and deliberate capacity investments by established players. For executives and capital allocators, the CAC market represents a structurally attractive but operationally complex environment where differentiation hinges on material performance, supply chain stability, and alignment with decarbonization and durability mandates.
Market Landscape and Structural Challenges
The revenue progression over the past five years illustrates a market that has recovered from earlier cyclical softness and is now entering a phase of disciplined expansion. The baseline year of 2025 anchors a forecast window extending through 2032, during which the market is expected to add roughly $690 million in incremental revenue. This trajectory reflects an industrial materials segment characterized by relatively high barriers to entry, application-specific formulation requirements, and steady replacement and retrofit demand rather than speculative volume growth. The concentration profile of the market reinforces this structure: the top three firms collectively account for approximately 43 percent of revenue, while the top five approach 60 percent. Such concentration signals the presence of entrenched technical expertise, established customer relationships, and scale advantages in specialized production, but it also leaves room for differentiated entrants and regional specialists to capture value in targeted segments.
Key Challenges and Inflection Points
Several structural pressures are reshaping how incumbents and new entrants compete. First, raw material dependency remains a persistent volatility driver. Bauxite feedstock sourcing is concentrated in a limited set of geographies, and procurement friction is a material share of supply planning complexity. Even with expectations of a modest alumina price decline in 2025, cost volatility tied to high-purity bauxite availability continues to influence margin planning and formulation economics. Second, the industry is navigating a transition in end-use engineering requirements. Steelmakers are increasingly moving toward electric-arc furnace configurations that demand alumina-rich refractory linings capable of withstanding temperatures above 1,700 degrees Celsius. This shift is not a simple volume story; it changes specification expectations, lining design assumptions, and the performance thresholds that CAC-based products must meet. Third, regulatory and standards adoption is gradually expanding the addressable use base in municipal and industrial infrastructure. The inclusion of sulfate-resistant calcium aluminate mortars in wastewater standards such as Australia’s WSA 160:2021 illustrates how specification changes can unlock new procurement pathways, but only when paired with local technical support, testing validation, and specification familiarity.
For decision-makers, these challenges translate into a clear operational mandate: growth will be captured by firms that can stabilize input costs, adapt formulations to higher thermal and chemical demands, and align with evolving standards rather than compete solely on price.
Calcined Alumina Market
Core Demand Drivers Shaping the Market
Technological Innovation and Performance Breakthroughs
Performance differentiation is becoming the primary battleground. CAC suppliers are expanding beyond commodity-grade offerings into specialized binders and refractory matrices that address longer service life, faster strength development, and greater resistance to thermal shock and chemical attack. Recent product introductions targeting improved thermal resistance and durability in steel and foundry environments reflect a broader industry push to support heavier operational loads and more aggressive process conditions. At the same time, enhanced binder portfolios are being developed for sustainable construction and high-performance refractory applications, signaling that technical Roadmaps are increasingly tied to durability, reduced maintenance frequency, and lifecycle performance. The commercial implication is straightforward: customers in refractory, infrastructure repair, and demanding construction applications are willing to pay for formulations that reduce downtime and extend replacement cycles, provided the supplier can demonstrate consistent quality and application support.
Policy and Regulatory Environment
Regulatory frameworks and technical standards are quietly re-shaping demand patterns. In wastewater and sewer infrastructure, specification changes that recognize sulfate-resistant calcium aluminate mortars create new acceptance pathways where conventional materials may underperform. Similarly, the growing adoption of thermal energy storage systems is introducing requirements for matrices that can endure hundreds of 600 to 650 degree Celsius cycles without losing mechanical strength. These are not marginal adjustments; they are design-level shifts that influence material selection at the engineering and procurement stages. For CAC producers, regulatory alignment offers a route to specification-led demand, but it also requires investment in testing, documentation, and technical collaboration with end users and engineering firms. Markets rarely move on raw material availability alone; standard-setting and certification often determine which materials become defaults in public infrastructure and industrial projects.
Demand-Side Shifts in Industrial and Infrastructure Behavior
Demand is being shaped by two reinforcing behaviors. In heavy industry, there is a growing preference for materials that can withstand more severe operating conditions while reducing maintenance windows. This is evident in refractory applications, which represent the largest use segment and continue to drive volume as linings are specified for higher thermal loads and longer campaign life. In parallel, infrastructure repair and wastewater applications are increasingly valued for rapid strength gain and chemical resistance, making CAC-based binders attractive where downtime is costly or environmental exposure is significant. The construction segment, while smaller in relative terms, benefits from specialty uses where durability and fast setting are decisive. The broader message is that CAC demand is becoming more application-anchored: growth is tied to performance needs rather than generalized construction activity.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures remain influenced by feedstock concentration and the operational complexity of producing high-purity calcium aluminate products. Bauxite sourcing concentration in Guinea and China, combined with procurement challenges linked to raw-material cost volatility, keeps supply planning under scrutiny even as alumina prices are projected to ease modestly. This environment rewards companies that secure reliable feedstock arrangements, optimize energy and processing efficiency, and maintain flexibility in formulation to adapt to input cost movements. Regional capacity additions also play a role in shaping cost-to-serve. Localized production can reduce delivery lead times and improve service levels for large customers, which is particularly important in refractory and infrastructure applications where just-in-time supply and technical responsiveness can influence purchasing decisions. Cost efficiency in this market is less about absolute lowest input price and more about predictable availability, consistent quality, and the ability to serve demanding specifications without disruption.
Competitive Landscape and Leadership Strategies
The CAC market is defined by a mix of globally positioned specialists and regionally anchored producers with strong technical reputations. Leadership in this space is not determined by scale alone; it is increasingly tied to portfolio depth, application engineering capabilities, and strategic capacity deployment. Several firms have taken visible steps that highlight where the competitive frontier is moving.
Calucem has accelerated production at its New Orleans facility to meet rising demand from infrastructure and refractory applications, a move that underscores the importance of regional capacity in serving North American demand with shorter lead times and stronger local support. Imerys has expanded its calcium aluminate cement portfolio with advanced low-carbon binders for sustainable construction and high-performance refractories, reflecting a dual focus on performance and sustainability-oriented product design. Almatis introduced next-generation calcium aluminate cement products aimed at improved thermal resistance and durability in steel and foundry sectors, directly addressing the higher specification thresholds associated with modern furnace and casting environments. Cementos Molins increased R&D investment for high-performance calcium aluminate binders used in wastewater and infrastructure repair, signaling a deliberate push into specification-driven maintenance and municipal applications. In parallel, Calderys established a lightweight monolithics facility in Fulton, Missouri, increasing regional capacity by 60 percent and reducing delivery times, an example of how localized manufacturing can improve competitiveness in service-intensive segments.
Strategic Positioning and Differentiation
A few patterns emerge from these moves. First, portfolio premiumization is evident. Leading suppliers are not simply expanding volume; they are developing grades that target specific performance profiles, from high-alumina formulations to low-carbon binders and specialized mortar systems. Second, application proximity matters. Companies are investing where customer needs are most intense, whether that means refractory service for steel and foundry operations, marine and industrial flooring solutions, or wastewater and repair applications that require sulfate resistance and rapid strength development. Third, capacity is being aligned with demand geography and service expectations. Regional expansion is being used not only to increase output but also to improve responsiveness and reduce logistics friction for key accounts.
Market Structure Evolution
The market is likely to remain moderately concentrated, with room for both consolidation and targeted segmentation. Concentration at the top creates advantages in technical reputation, global supply coordination, and the ability to support large multinational customers across multiple regions. At the same time, the diversity of applications, grades, and regional standards creates opportunities for specialists that can dominate a particular use case or geography. New entrants face real barriers, including formulation know-how, qualification cycles, and feedstock access, but disruption is possible where a company brings a clearly differentiated value proposition, such as a novel binder architecture, superior cycle resistance for thermal storage applications, or a cost-effective regional supply model. The more probable evolution is not a single dominant wave of consolidation, but a continued mix of global leaders, regional specialists, and application-focused innovators competing on performance, service, and supply reliability.
Forward Outlook: Three Trends to Watch
Trend One: Specification-Led Demand in Infrastructure and Industrial Maintenance
Over the next several years, standards adoption and engineering preference shifts are expected to continue expanding CAC use in wastewater, sewer renewal, and industrial repair. The trend is not about sudden volume spikes; it is about a gradual but durable shift toward materials that meet more demanding chemical and durability requirements. Commercial opportunities lie in technical sales, specification support, and localized testing validation. Companies that invest in helping engineers and procurement teams understand sulfate resistance, rapid strength gain, and lifecycle cost advantages are better positioned to convert standards changes into recurring demand. The risk is that specification adoption can be slow and region-specific, requiring patience and sustained engagement rather than assuming immediate market pull.
Sodium Aluminate Market
Trend Two: Higher Thermal and Mechanical Performance Requirements in Refractories
As steelmaking and foundry operations adopt processes that push temperature and wear thresholds higher, refractory specifications will increasingly require alumina-rich linings and CAC-based matrices that maintain integrity under severe thermal cycling and mechanical stress. This trend favors suppliers with robust high-performance grades, consistent quality control, and the ability to support lining design and installation practices. The opportunity is to move from transactional supply to engineered solutions, where material selection is tied to campaign length, maintenance scheduling, and operational reliability. The uncertainty is that process changes can be uneven across regions and customers, and not every shift translates into immediate demand for premium grades if economics or operating strategies change.
Trend Three: Regional Capacity and Supply Chain Resilience Becoming Competitive Advantages
Given feedstock concentration and cost volatility, regional production and supply reliability are becoming differentiators rather than optional efficiencies. Near-customer capacity reduces delivery risk, supports large project timelines, and strengthens relationships with buyers who prioritize service continuity. Over the next few years, competitive advantage will increasingly accrue to companies that can combine formulation expertise with dependable supply and favorable cost-to-serve. This does not require universal scale; it requires strategic placement of capacity, disciplined feedstock management, and operational flexibility. The downside is that capacity additions and feedstock strategy carry capital and execution risk, and overinvestment in one region can leave a company exposed if demand patterns shift or input costs behave unexpectedly.
Strategic Implications for Decision-Makers
For Manufacturers and Suppliers
Focus on performance differentiation and application closeness rather than competing primarily on base commodity pricing. Develop and document grades that address specific high-value needs, such as higher thermal resistance, sulfate resistance, rapid strength development, and improved cycle durability for thermal storage environments. Invest in technical support and qualification assistance so that specification changes translate into actual adoption. Build feedstock and production strategies that reduce exposure to raw-material volatility while preserving the ability to serve key regions with shorter lead times. Consider targeted capacity additions where service levels and regional demand justify the investment, but avoid expanding without clear application pull and customer commitment.
For Investors and Capital Allocators
Evaluate CAC exposures through the lens of application mix, feedstock security, and regional service capability rather than headline market size alone. Segments tied to refractory performance, infrastructure repair, and specification-driven wastewater applications offer durable demand characteristics, but returns depend on execution, formulation leadership, and cost discipline. Watch for signals such as R&D emphasis on low-carbon binders and high-performance grades, localized capacity expansions, and standards adoption that broaden the specification base. Be mindful of concentration risk in feedstocks and the potential for margin pressure if input volatility persists despite easing alumina prices. The most resilient business models will likely be those that combine technical differentiation with dependable supply and the ability to serve demanding customers in multiple geographies.
For Procurement and Engineering Leaders
Treat CAC selection as a lifecycle decision rather than a transactional purchase. Where applications involve chemical exposure, thermal cycling, fast turnaround requirements, or long service life expectations, evaluate total cost of ownership including downtime, maintenance frequency, and replacement risk. Engage early with suppliers that can provide specification support, testing data, and application guidance, especially in projects governed by evolving standards or demanding operating conditions. Secure supply commitments where continuity matters, and consider regional sourcing options that reduce delivery risk for critical infrastructure and industrial maintenance programs. Procurement choices made with performance and reliability in mind can materially affect operational outcomes over the life of an asset.
Conclusion
The Calcium Aluminate Cement market is entering a phase where growth is increasingly tied to performance requirements, specification acceptance, and supply reliability. Steady revenue expansion toward the end of the decade reflects the material’s role in refractory durability, infrastructure resilience, and specialized industrial applications, but realizing commercial advantage requires more than exposure to a growing market. It demands formulation leadership, disciplined feedstock strategy, regional service capability, and the ability to convert engineering and standards shifts into qualified demand. For organizations operating in or adjacent to this space, the most valuable next step is to move from broad market awareness to precise segmentation, application-specific economics, and region-level supply strategy. Detailed segmentation data, regional breakdowns, and tailored strategic recommendations can sharpen those decisions and support more confident planning in a market where performance, standards, and supply chain resilience increasingly determine who captures value.
For detailed analysis of this topic, please visit the official page: Calcium Aluminate Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Grain Combine Harvester Market: Why 4.85% CAGR Signals 2032 Growth Shifts
By pmarketresearch, 2026-09-21
The Grain Combine Harvester Market: Strategic Trends and Commercial Opportunities Through 2032
The global grain combine harvester market has entered a phase of measured expansion, transitioning from volume-driven growth to value-focused evolution. Valued at approximately 120.0 million USD in 2020, the market has grown steadily through 2025,当今 reaching 165.0 million USD, and is projected to advance to 235.0 million USD by 2032. This trajectory reflects a compound annual growth rate of 4.85 percent over the forecast horizon, signaling steady but not explosive demand. The pace of expansion underscores a sector that is maturing technologically while grappling with structural pressures ranging from labor scarcity to regulatory compliance. For executives and investors, the critical question is no longer whether the market will grow, but how value will be captured across different equipment segments, geographies, and technology adoption curves.
Worldwide Cabbage Harvester Market
Despite the positive numerical trajectory, the industry faces several inflection points that will reshape competitive dynamics over the next half decade. Grain harvesting operations are increasingly constrained by tightening harvest windows, driven by climate variability and the need to minimize post-harvest losses. Simultaneously, the cost of ownership is rising as emission standards tighten and precision technology becomes a baseline expectation rather than an optional upgrade. These pressures are forcing manufacturers and fleet operators to rethink procurement strategies, service models, and equipment configurations. The market is also witnessing a concentration of share among established players, with the top three firms accounting for roughly 65 percent of revenue and the top five capturing approximately 85 percent. Such concentration suggests high barriers to entry in premium segments, while creating space for specialized manufacturers to compete on cost, regional adaptability, and niche crop requirements.
Another structural challenge lies in the uneven pace of technology adoption across farming scales and regions. Large commercial operations are rapidly integrating automation, telematics, and data-driven decision tools, while smaller and mid-sized farms often face capital constraints that slow upgrades. This divergence creates a bifurcated market where premium, technology-rich equipment coexists with cost-sensitive, mechanically robust alternatives. Manufacturers must navigate this split without diluting brand equity or overextending service networks. For buyers, the challenge is to align equipment selection with actual operational needs rather than aspirational specifications, avoiding overinvestment in features that deliver limited return under local conditions.
Key Drivers of Market Change
Technological Innovation and Precision Automation
Technology is the most visible catalyst reshaping combine harvester demand and value propositions. Recent product updates from leading manufacturers highlight a clear trajectory toward automation that reduces operator workload, improves consistency, and helps farmers meet narrow harvest windows. In March 2026, one major manufacturer updated its flagship X9 and S7 series with enhanced harvest settings automation, predictive ground speed automation, and expanded operator aids. These features are designed to optimize threshing and separation parameters in real time, adapting to varying crop conditions without constant manual intervention. Such capabilities directly address the operational reality that harvest efficiency depends not only on machine capacity but on the consistency of adjustments across varying field conditions.
The broader implication is that precision technology is becoming a differentiator that influences both purchase decisions and residual equipment value. Machines that can maintain optimal performance with fewer operator inputs reduce labor dependency and lower the risk of costly errors during peak harvest periods. They also generate operational data that can be integrated into farm management systems, creating a pathway toward service contracts and recurring revenue streams for manufacturers. For industry participants, the strategic question is how to balance the complexity of automated systems with reliability, serviceability, and total cost of ownership. Overly intricate systems can increase downtime if support networks are not adequately scaled, while well-executed automation delivers measurable efficiency gains that justify premium pricing.
Policy and Regulatory Environment
Regulatory pressure on emissions and equipment standards continues to shape product architectures and procurement timelines. Modern combine engines are increasingly designed to comply with stringent emission regulations, often incorporating advanced aftertreatment systems. For example, certain combine platforms now rely on third-generation selective catalytic reduction technology integrated with proprietary engine architectures to meet evolving standards. While such compliance measures add engineering complexity and upfront cost, they also align equipment with long-term regulatory trajectories, reducing the risk of stranded assets as jurisdictions tighten emission limits.
Beyond emissions, policy environments influence market dynamics through subsidy structures, agricultural modernization programs, and regional trade conditions. In markets where government support targets mechanization or productivity upgrades, demand can accelerate for both new equipment and retrofit solutions. Conversely, periods of policy uncertainty or subsidy reduction can delay capital expenditures, pushing buyers toward used equipment or extended service life for existing machines. Manufacturers with flexible financing, transparent compliance roadmaps, and region-specific product configurations are better positioned to navigate these fluctuations. The regulatory dimension also interacts with technology adoption, as emission-compliant engines often pair with electronic control systems that enable the precision features discussed above, creating a convergence of compliance and performance benefits.
Demand-Side Shifts in Crop Patterns and Operational Scale
Demand for combine harvesters is fundamentally linked to what farmers grow and how they organize their operations. Cereal crops continue to represent the largest application segment, followed by oilseeds and other crops, reflecting the enduring importance of staple grains and the expanding role of oilseed production in rotation systems and demand for vegetable oils. This crop mix influences equipment preferences, header configurations, and threshing system design. For instance, cereal-focused operations may prioritize high-capacity grain handling and uniform threshing, while oilseed and specialty crop operations often require gentler handling to preserve quality and reduce losses.
At the same time, farm operational patterns are shifting. Larger, more consolidated farming enterprises are seeking equipment that maximizes throughput during compressed harvest periods, while also reducing labor intensity. This drives demand for machines with larger grain tanks, faster header systems, and improved cleaning and separation components that maintain grain quality under high throughput. Meanwhile, smaller operators often weigh whether to invest in full-scale combines or to explore alternative configurations that balance capacity with cost. The demand side is therefore not monolithic; it is segmented by crop portfolio, farm scale, and the willingness to adopt technology that changes operating economics. Manufacturers and dealers that can map these demand patterns to specific product lines and service offerings gain an advantage in matching solutions to real-world needs.
PW Consulting Automotive & Machinery Research Center
Supply Chain and Cost Structure Dynamics
Cost structures across the combine harvester value chain are influenced by component availability, manufacturing localization, and the economics of aftertreatment and electronic systems. The shift toward more sophisticated engines and electronics increases dependency on specialized parts and calibrated service procedures. This can raise maintenance costs and extend lead times for certain components, particularly in regions where service networks are still developing. At the same time, manufacturers that localize production or streamline supply chains can mitigate cost pressures and respond more quickly to regional demand fluctuations.
Combine Harvesters Market
The cost equation also extends to the total cost of ownership perspective that increasingly guides procurement decisions. Buyers are weighing not only purchase price but fuel efficiency, parts availability, warranty terms, and the cost of integrating machines into existing farm data ecosystems. Equipment that offers predictable operating costs and supports remote diagnostics can reduce downtime and service surprises, which are critical during harvest when delays translate directly into crop loss. Supply chain resilience therefore becomes a competitive attribute, not merely an operational concern. Companies that can guarantee component availability, standardize service procedures across regions, and provide transparent cost projections are better positioned to win confidence in a market where buyers are increasingly cautious about long-term commitments.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a small group of globally established manufacturers, each pursuing distinct strategic positioning. One major American-based manufacturer has emphasized high-capacity platforms with advanced automation, targeting large-scale operations that prioritize throughput and consistency. Its recent updates to flagship series reflect a focus on reducing operator workload and improving adaptability across variable harvest conditions, reinforcing a premium, technology-forward brand image. Another European manufacturer has built its reputation on versatile, high-productivity platforms designed for maximum operational availability, with product families that span different capacity tiers and crop requirements. This approach appeals to operators who value flexibility and uptime across diverse farming conditions.
A third major player has concentrated on twin-rotor architectures and header innovations that emphasize grain quality preservation and quick adjustments, targeting buyers who want high capacity without compromising crop integrity. Its model year updates have introduced improved header systems, new electronics, and faster knife advance settings, illustrating a strategy centered on operational speed and grain quality. A fourth global group has leveraged multiple brands and hybrid combine lines to serve a broad customer base, combining efficient threshing and cleaning systems with durable construction, and aligning engine designs with emission compliance requirements. This multi-brand structure allows the group to address different price points and regional preferences while maintaining engineering consistency.
Alongside these global leaders, specialized manufacturers have carved out positions by focusing on particular crops, regional markets, and export-oriented production. One China-based company specializes in combine harvesters and spare parts for rice, corn, and other crops, with an emphasis on ISO-certified production and export-focused manufacturing. This profile highlights a strategy of competitive cost, crop-specific engineering, and global distribution, appealing to buyers who prioritize value and crop suitability over premium brand positioning. Such specialists often benefit from lower overhead and the ability to tailor parameters to regional crop characteristics, though they must also navigate service network development and perceptions of long-term reliability in foreign markets.
The market landscape is evolving through a combination of consolidation among premium players and differentiation by specialists. High concentration among top firms indicates that scale, brand recognition, and global service infrastructure confer advantages in the upper segment of the market. At the same time, the presence of capable niche manufacturers suggests that differentiation by crop type, regional adaptation, and cost efficiency remains viable, particularly where buyers are less sensitive to brand prestige and more focused on functionality and total cost. New entrants face the challenge of establishing trust in a sector where downtime during harvest is costly, but opportunities exist in underserved crop segments, emerging regions, and applications where specialized configurations deliver clear operational advantages. The trend is therefore not toward uniform convergence but toward a layered market in which premium platforms, versatile mid-range machines, and crop-specific solutions coexist, each competing on distinct value propositions.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Automation Moves from Differentiator to Baseline Expectation
The trajectory of recent product updates indicates that automation features will shift from premium add-ons to standard capabilities in most new machines. Predictive ground speed control, automated harvest settings, and operator aids that reduce manual adjustments are becoming integral to maintaining efficiency during tight harvest windows. Over the next three to five years, machines lacking these capabilities may face growing scrutiny, particularly in markets where labor availability is limited and the cost of harvest delays is high. This trend creates opportunities for manufacturers to standardize automation across product tiers, while also raising the bar for service training, software support, and parts availability. The commercial opportunity lies in bundling automation with service contracts, data services, and remote diagnostics, transforming equipment purchases into longer-term partnerships. The risk is that automation complexity outpaces support capacity, leading to downtime or customer dissatisfaction if systems are not robustly engineered and well-supported in the field.
Crop Quality and Regional Adaptation Drive Configuration Innovation
As crop portfolios diversify and quality requirements tighten, configuration innovation will increasingly focus on preserving grain integrity and adapting to local crop characteristics. Header designs, rotor geometries, and cleaning systems that balance high throughput with gentle handling will gain relevance, especially for oilseeds and specialty crops where quality preservation directly affects market value. Regional adaptation will also matter more as manufacturers address varied crop mixes, field conditions, and operational scales. Companies that offer modular headers, adjustable threshing parameters, and clear guidance on crop-specific setups can capture demand from buyers who need flexibility without sacrificing efficiency. The opportunity is to build product architectures that allow faster, more precise configuration changes, reducing setup time and improving consistency across varied crops. The uncertainty lies in predicting which regional crop patterns will persist and how quickly new varieties or rotation practices will alter equipment requirements.
Total Cost of Ownership and Compliance Shape Procurement Decisions
Procurement is increasingly evaluated through the lens of total cost of ownership, with emission compliance, fuel efficiency, service predictability, and integration with farm data systems weighing heavily in purchase decisions. Machines that align with current and anticipated regulatory standards reduce the risk of premature obsolescence, while those with transparent service costs and reliable parts availability lower the financial uncertainty of ownership. This trend benefits manufacturers that can provide clear compliance roadmaps, standardized service procedures, and predictable operating cost projections. It also encourages interest in refurbished, remanufactured, and extended-service options for cost-conscious buyers, creating ancillary market segments around parts, upgrades, and lifecycle management. The downside risk is that regulatory shifts or supply disruptions for emission-related components could increase costs or delay deployments, particularly in regions where compliance infrastructure is still developing. Strategic planning therefore requires not only attention to current standards but also scenario planning for future regulatory trajectories and component availability.
Strategic Recommendations for Decision-Makers
For Equipment Manufacturers and Brand strategists
Focus on standardizing automation and precision features across product tiers while ensuring service networks can support them. Differentiation will increasingly come from reliability, ease of configuration, and the quality of data and service ecosystems rather than from feature count alone. Invest in modular architectures that allow flexible header and threshing configurations for varied crops, and develop clear crop-specific guidance that helps buyers match equipment to their actual operating profile. Strengthen regional service capacity and parts availability, particularly for emission-related components and electronic systems, to reduce downtime risk and build trust in markets where service responsiveness is a key purchase factor. Consider lifecycle offerings such as remote diagnostics, predictive maintenance, and flexible financing to create recurring value and reduce barriers to adoption for mid-sized operators.
For Investors and Market Participants
Assess value creation opportunities across the layered market rather than assuming uniform growth. Premium automation platforms offer margin potential but require strong service and software support to sustain customer satisfaction. Cost-competitive, crop-specific specialists may capture share in regions and applications where price and functionality matter more than brand prestige. Pay attention to the compliance and supply chain dimension, since emission-related components and electronic systems can influence cost structures and lead times. Evaluate companies based on their ability to manage total cost of ownership narratives, maintain component availability, and adapt product configurations to regional crop patterns. Also watch for consolidation activity among premium players and for potential specialization plays in underserved crop segments or emerging regions where mechanization demand is rising but premium brand presence is less dense.
For Procurement Leaders and Farm Operations
Align equipment selection with actual crop mix, harvest window constraints, and labor availability rather than chasing maximum specifications. Evaluate total cost of ownership including fuel efficiency, service responsiveness, parts availability, and compliance alignment, not just purchase price. When considering automation features, prioritize those that demonstrably reduce operator workload and improve consistency under local field conditions, and verify that service support and training are available before committing. For operations with mixed crops or variable field conditions, favor configurations that allow quick adjustments and modular headers to preserve quality and maintain throughput across different tasks. Where capital constraints are significant, explore lifecycle options such as certified refurbished units, parts and service agreements, and flexible financing that preserve operational capacity without overstretching budgets.
The grain combine harvester market is evolving along multiple axes at once: automation is becoming central to operational efficiency, regulatory and compliance pressures are shaping product architectures, and demand patterns are increasingly defined by crop portfolios and operational scale. These forces create a market in which competitive advantage depends on matching technology, configuration, and service to real-world conditions rather than on generic capacity claims. For those seeking to navigate this landscape with precision, a deeper dive into segment-level dynamics, regional demand patterns, and company-specific strategies can sharpen planning and reduce uncertainty. The full research report provides detailed segmentation data, regional breakdowns, and tailored recommendations to support more granular decision-making across manufacturing, investment, and procurement contexts.
For detailed analysis of this topic, please visit the official page: Grain Combine Harvester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Imperatives in the Biaxially Oriented Polyamide (Nylon) Film Market: Navigating Growth, Volatility, and Sustainability
The biaxially oriented polyamide (BOPA) film market stands at a critical inflection point where traditional growth trajectories intersect with transformative pressure from raw material volatility, sustainability mandates, and shifting end-user expectations. Over the 2020–2025 historical period, the global BOPA film revenue expanded from approximately $1,170 million to $1,430 million, reflecting an average annual growth rate of roughly 4.2% in absolute terms. As the market enters the 2026–2032 forecast window, industry momentum is expected to accelerate, with a projected compound annual growth rate of 5.8%, pushing total revenue toward $2,088 million by the end of the decade. This expansion is not merely a continuation of historical demand patterns. It reflects a structural reconfiguration of how packaging, pharmaceutical, and industrial supply chains value barrier performance, mechanical durability, transparency, and increasingly, the carbon footprint embedded in film production.
For executives and strategic planners, this trajectory presents both a sizable addressable market and a complex operating environment. Growth is broad-based but uneven, shaped by regional manufacturing capabilities, regulatory divergence, and the concentration of value creation among a cohort of globally active producers. The following analysis examines the market’s current architecture, the forces reshaping its dynamics, the strategic positioning of leading participants, and the actionable implications for manufacturers, investors, and procurement teams navigating the next five years.
Market Architecture and Core Challenges
The BOPA film market operates within a moderately concentrated structure where scale, technology access, and application specialization determine competitive advantage. Revenue distribution spans multiple geographies and value chains, with Asia Pacific accounting for the largest share of global revenue, followed by Europe and North America. Latin America and the Middle East & Africa represent smaller but strategically relevant demand pools, often characterized by cost-sensitive industrial applications and emerging packaging consumption. Rather than competing purely on price, participants are increasingly differentiating through sequential versus simultaneous orientation technologies, gauge control, clarity, puncture resistance, and compatibility with laminates and heat-seal systems. The market’s oligopolistic tilt means that margin preservation depends on technical service, supply reliability, and the ability to anticipate downstream requirements in food safety, pharmaceutical compliance, and industrial durability.
Biaxially Oriented Polyamide (BOPA) Films Market
Despite the favorable growth backdrop, three structural challenges are reshaping the operating logic of the BOPA film sector:
- Raw material price sensitivity and input volatility. BOPA production depends on polyamide resins whose pricing is closely tied to caprolactam and adiponitrile dynamics, energy costs, and regional supply balances. Recent price adjustments in the nylon value chain have increased pressure on converters and film manufacturers, squeezing margins unless absorbed through product premiumization, contract structuring, or efficiency gains.
- Regulatory fragmentation and trade barriers. Divergent packaging regulations, anti-dumping measures, and evolving sustainability certification expectations are fragmenting what was once a relatively standardized export market. Producers now face a patchwork of obligations that affect cost, eligibility, and time-to-market for new grades.
- Sustainability expectations as a procurement imperative. End users are increasingly embedding environmental criteria into supplier selection, not simply as compliance but as part of brand positioning and risk management. Films with lower carbon intensity, recyclability alignment, and certified sustainable feedstocks are moving from niche differentiators to baseline requirements in certain segments.
These challenges are not isolated. They interact with one another, creating a landscape where cost, compliance, and customer expectations must be managed simultaneously. The firms that navigate this triad most effectively will be those that treat sustainability and regulatory adaptation as design parameters rather than afterthoughts, and that use technical differentiation to justify price realizations in a rising-cost environment.
Key Drivers Reshaping the BOPA Film Market
Technology Innovation and Performance Differentiation
Performance advancement remains the central engine of value creation in BOPA films. Sequential and simultaneous orientation processes continue to evolve, enabling tighter control over dimensional stability, barrier properties, and optical clarity. For pharmaceutical packaging and specialty high-barrier applications, this translates into films that maintain integrity under strict processing conditions and extended shelf-life requirements. For food packaging, improvements in tensile strength, sealability, and moisture resistance support thinner gauges and more flexible laminates without compromising protection. The strategic significance of these advances lies in their ability to shift competition away from commodity substitution and toward application-specific value. When a film can enable lighter structures, reduce waste in downstream converting, or improve reliability in sensitive applications, it becomes a strategic input rather than a replaceable component.
Recent dynamics underscore the importance of feedstock reliability in supporting these technical goals. In North America, price adjustments for caprolactam and polyamide grades have been announced for 2026, reflecting evolving conditions across the nylon value chain. At the same time, spot pricing for caprolactam has shown month-over-month increases in both North American and European markets. For BOPA producers, this environment rewards integrated planning, long-term supply agreements, and grade architectures that maintain performance even as input economics fluctuate. It also elevates the strategic importance of alternative feedstocks and certified sustainable options, particularly where customers view supply continuity and environmental credentials as linked priorities.
Policy, Trade, and Certification Shifts
The regulatory environment is becoming a more active determinant of market access and competitive positioning. Trade measures have already begun to reshape regional dynamics. For example, Indonesia has imposed anti-dumping duties on nylon film imports from China, Thailand, and Taiwan, with a multi-year validity period. Such measures influence not only the cost structure of imported films but also the broader pattern of regional sourcing, inventory positioning, and local manufacturing incentives. In parallel, certification frameworks are gaining commercial relevance. ISCC PLUS certification and product carbon footprint disclosures are increasingly referenced in customer evaluations, especially where end brands are under pressure to communicate environmental progress credibly.
These policy and certification developments have a dual effect. They raise the bar for market entry and expansion in affected geographies, but they also reward firms that can demonstrate verifiable sustainability claims and adapt their supply footprint to regional trade realities. For BOPA manufacturers, the implication is that geographic strategy can no longer be separated from compliance strategy. Production capacity, feedstock sourcing, and documentation capability are now part of the same commercial equation.
Demand-Side Evolution Across Packaging Ecosystems
Demand for BOPA films continues to be anchored by food packaging, pharmaceuticals, and industrial applications, each with distinct performance and regulatory profiles. Food packaging remains the largest application driver, supported by the need for barrier protection, clarity, and compatibility with flexible packaging formats. Pharmaceutical packaging demands high consistency, integrity, and traceability, making film quality and process stability especially important. Industrial packaging adds another layer of requirements around puncture resistance, durability, and cost efficiency in heavier-duty uses.
What is changing is the way these demand segments evaluate film suppliers. Procurement decisions are increasingly multidimensional, weighing technical fit alongside availability, sustainability attributes, and total cost of ownership rather than unit price alone. This shift is especially visible in markets where brand owners and converters are seeking to reduce material intensity, improve recyclability outcomes, or align with corporate sustainability commitments. In that context, BOPA films that support ultra-thin constructions, recyclable laminate designs, or carbon footprint reduction become more commercially attractive, even if they carry a premium relative to baseline alternatives.
Supply Chain and Cost Structure Dynamics
Cost structures across the BOPA value chain are being redefined by several simultaneous forces. Energy prices, resin availability, logistics, and regional manufacturing footprints all influence competitive positioning. At the same time, some producers are pursuing lower-cost manufacturing models for food and industrial packaging, while others are emphasizing high-performance grades for demanding applications. This bifurcation creates a market where cost leadership and technology leadership are not always pursued by the same players, and where the strategic challenge is to avoid being trapped in the middle of a segment that is simultaneously price-sensitive and performance-driven.
Certification and sustainability investments are adding a new layer to cost structure considerations. Obtaining environmental certifications for production facilities and rolling out lower-carbon grades requires upfront investment and disciplined execution. Yet these capabilities can also become durable advantages when customers begin to prioritize verifiable claims and supply assurance over spot-market pricing alone. The result is a market in which cost discipline and positioning clarity are both necessary, and in which the most resilient firms are those that can select the segments where their cost model and capabilities are best aligned.
Competitive Landscape and Strategic Positioning
The BOPA film competitive field includes globally established specialty producers, regionally focused manufacturers, and firms that balance cost efficiency with targeted performance differentiation. Several Japanese and Korean companies occupy a prominent role in high-quality sequential BOPA films, particularly where pharmaceutical packaging, high-barrier applications, and demanding food packaging formats are involved. Their positioning tends to emphasize sequential and simultaneous orientation expertise, consistent gauge control, and specialized barrier and mechanical attributes. This enables them to compete on reliability and application support, not only on price.
European participants contribute another dimension to the landscape. Certain manufacturers have focused on sustainable grades, recyclable laminate compatibility, and ultra-thin options that align with packaging 경량화 and environmental goals. Others have expanded sustainability credentials through ISCC PLUS certification and lower-carbon product claims, linking production credentials directly to customer-facing value propositions. In this group, the strategic emphasis is often on demonstrating measurable environmental improvement while maintaining the performance required by converters and end users.
In Asia, a broader set of producers supports regional and export demand across food, industrial, and specialty packaging. Some companies emphasize cost-effective manufacturing for high-volume applications, while others concentrate on PA6-based solutions or enhanced barrier and mechanical performance. This diversity creates a competitive environment in which regional price dynamics, local content expectations, and application specialization all matter. It also means that trade measures and regional certification requirements can quickly alter the relative attractiveness of different sourcing options.
Beyond firm-level positioning, the market is exhibiting several structural trends:
- Consolidation pressure in specialty segments. Where performance, compliance, and technical service are critical, larger or more integrated players can gain share by offering consistent supply, multi-grade portfolios, and stronger application support.
- Segmentation between cost-driven and value-driven production. Not all BOPA films compete in the same decision framework. High-barrier and pharmaceutical-oriented films reward precision and certification; certain industrial and food packaging applications remain more sensitive to cost and local availability.
- Growing relevance of sustainability as a competitive attribute. Lower-carbon grades, certified feedstocks, and recyclable laminate alignment are becoming part of the value proposition in select markets, especially where brand owners and converters are building sustainability into purchasing criteria.
- Regional reconfiguration of supply patterns. Trade measures and certification expectations are encouraging buyers to diversify supply sources or localize production where feasible, increasing the strategic importance of regional manufacturing and compliance readiness.
Taken together, these trends suggest a market that is moving toward greater segmentation and more explicit differentiation. The firms most likely to sustain favorable positioning are those that can define their competitive lane clearly, whether that lane is high-performance specialty films, cost-efficient regional supply, or sustainability-linked product architecture, and then execute with discipline in that lane.
Forward-Looking Trends and Commercial Implications
Trend 1: Sustainability Moves from Differentiator to Procurement Filter
Over the next three to five years, environmental criteria are likely to become more deeply embedded in BOPA film purchasing decisions, particularly in segments connected to consumer-facing brands and regulated packaging ecosystems. This does not mean every buyer will require the same standard, but it does mean that verifiable sustainability attributes, including certified feedstocks and product carbon footprint reductions, will increasingly influence supplier shortlists.
The commercial opportunity lies in linking sustainability claims to real performance and supply reliability. Films that combine lower carbon intensity with acceptable barrier, clarity, and mechanical properties can capture premium positioning in applications where environmental alignment matters. The risk is greenwashing exposure if claims are not substantiated or if sustainability improvements undermine the functional requirements that customers depend on. Firms will need to manage this balance carefully, with transparent documentation and product design that integrates sustainability without sacrificing performance.
Trend 2: Input Volatility Will Reward Integrated Strategy and Grade Architecture
Raw material and energy volatility are expected to remain features of the operating environment, not temporary disruptions. This will continue to pressure margins and elevate the importance of procurement strategy, hedging approaches, product mix management, and operational efficiency. In this context, the most resilient BOPA businesses are likely to be those that can adjust grade architecture to emphasize higher-value applications when cost pressure intensifies, while maintaining reliable supply for cost-sensitive segments.
The opportunity here is partly defensive and partly offensive. Defensively, stronger supply relationships and flexible sourcing can reduce exposure to spot-market shocks. Offensively, firms that can sustain consistent quality and performance despite input volatility can strengthen customer trust and justify more stable pricing relationships. The uncertainty is the pace and direction of feedstock and energy price movements, which can differ by region and shift quickly in response to broader market conditions.
Trend 3: Regionalization and Trade Policy Will Reshape Sourcing Maps
Trade measures, local content expectations, and certification requirements are likely to continue encouraging regionalization in BOPA supply chains. Buyers may increasingly prefer regional production or diversified sourcing to reduce exposure to duties, logistics risk, and compliance complexity. This favors producers with flexible manufacturing footprints, strong regional compliance capabilities, and the ability to serve local demand with consistent quality.
The strategic opportunity is to position capacity and product portfolios where regulatory and trade dynamics are most favorable, while maintaining the ability to serve export demand where it remains viable. The risk is that protectionist measures and regulatory divergence could fragment what remains a global technology market, increasing complexity and reducing the efficiency of scale-based strategies in some geographies. Participants will need to monitor policy developments closely and align sourcing and capacity decisions with evolving market access conditions.
Thermoplastic Polyamide Market
Strategic Actions for Decision-Makers
For manufacturing and strategy leaders, the priority is to align product positioning with the segments where performance and sustainability can be monetized most effectively. This means resisting the temptation to compete uniformly across all applications and instead selecting where sequential or simultaneous orientation technologies, barrier performance, and certified sustainable grades create genuine value. It also means building procurement and supply resilience into the operating model, especially given raw material price movements and regional trade dynamics. Manufacturers that can offer reliable supply, clear documentation, and application-specific technical support will be better placed to preserve margins and customer relationships in a volatile environment.
For investors and corporate development teams, the key question is where value is likely to concentrate as the market matures. The most attractive exposures are probably in firms with clear competitive differentiation, credible sustainability capabilities, and positioning that matches regional demand growth rather than broad, undifferentiated capacity expansion. Equally important is the risk side: exposure to input cost shocks, trade barriers, and commoditization in price-sensitive segments can erode returns if not managed through portfolio design and segment selection. Due diligence should therefore focus not only on capacity and revenue trend, but also on certification readiness, feedstock strategy, regional market access, and the defensibility of technical differentiation.
PW Consulting
For procurement and sourcing professionals, the strategic shift is to evaluate BOPA films through a broader lens that includes sustainability documentation, supply continuity, and total cost of ownership rather than unit price alone. When films are critical to product integrity or brand positioning, the cost of inconsistency, supply disruption, or misalignment with sustainability expectations can outweigh modest price differences. Diversifying qualified suppliers by capability and region, understanding certification status, and clarifying performance requirements with converters and internal stakeholders can reduce exposure while creating room to capture value from specialized films where they are justified.
For all of these audiences, the practical takeaway is that BOPA film strategy is no longer solely about film properties or price. It is about aligning technology, compliance, sustainability, and regional supply dynamics with the specific applications that matter most to each business. The market’s growth trajectory provides room for value creation, but capturing that value will increasingly depend on precision in positioning and discipline in execution.
The dynamics described here are broad in scope, but their real impact is highly segment-specific and region-specific. Detailed segmentation data, regional revenue breakdowns, competitor benchmarking, and customized scenario analysis can materially sharpen strategic decisions, particularly for organizations evaluating capacity investments, supplier qualification, product roadmap planning, or market-entry timing. For teams that require a more granular view of segment growth paths, competitive positioning, and application-level demand shifts, PW Consulting’s full market research report provides deeper segmentation detail and tailored analytical frameworks to support concrete business decisions.
For detailed analysis of this topic, please visit the official page: Biaxially Oriented Polyamide (nylon) Film (BOPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Navigating the Plasma Etch System Market: Strategic Trends and Commercial Opportunities Through 2032
The plasma etch system market has entered a phase of sustained expansion, driven by relentless demand for miniaturization, advanced packaging, and specialized surface engineering across multiple high-tech sectors. Historical data from 2020 through 2025 shows a market trajectory that has consistently outpaced broader semiconductor equipment cycles, with revenues climbing from approximately 163 million to 215 million over that span. The forward curve suggests continued momentum, with the market projected to exceed 344 million by 2032, reflecting a compound annual growth rate of roughly 13.5 percent. This expansion is not merely a function of cyclical upturns; it represents structural shifts in how manufacturers approach material removal, surface modification, and precision patterning at increasingly aggressive technology nodes.
Yet the headline growth figures only tell part of the story. Beneath the surface, the market is navigating a complex set of operational, regulatory, and competitive pressures that are reshaping how equipment suppliers design, sell, and support plasma etch platforms. For executives and investors evaluating exposure to this space, understanding the interplay between technology roadmaps, cost structures, and policy mandates is essential to positioning for the next phase of value creation.
Mapping the Current Landscape and Defining Constraints
The revenue distribution across regions highlights a globally dispersed but increasingly interconnected demand base, with Asia Pacific and North America together accounting for the largest share of system placements. Europe maintains a meaningful footprint, while Latin America and the Middle East and Africa represent smaller but steadily developing markets. This geographic spread matters because it means equipment suppliers cannot rely on a single demand engine; they must calibrate product portfolios, service networks, and application expertise to reflect regional priorities ranging from logic and memory scaling to specialty compound semiconductor processing.
By technology type, inductively coupled plasma systems dominate the installed base, reflecting their versatility across a broad range of etching and surface treatment tasks. Reactive ion etching and deep reactive ion etching solutions occupy smaller but strategically important niches, particularly where vertical sidewall profiles, high aspect ratio features, or specialized throughput requirements dictate the choice of platform. On the application side, the semiconductor industry remains the dominant destination for plasma etch systems, with medical device manufacturing and electronics and microelectronics applications representing meaningful but comparatively smaller revenue pools. This concentration underscores a simple reality: semiconductor roadmaps continue to pull the bulk of investment and innovation, but adjacent sectors are increasingly willing to invest in tailored plasma processing capabilities when the performance argument is clear.
Dry Etching Equipment Market
Several structural challenges are testing the resilience of supplier strategies and buyer planning:
- Regulatory tightening around etch gases and chamber emissions. Environmental mandates are moving from aspirational targets to enforceable reduction pathways. In the United States, the EPA's AIM Act sets aggressive production and consumption reduction goals for hydrofluorocarbons over a fifteen-year horizon, directly affecting the use of gases common in plasma etch processes. In Europe, F-gas regulations are compressing allowable emissions of HFCs and hydrofluoroolefins, with targets to cut emissions to two-thirds of 2014 levels by 2030. These policies are not abstract: utilities and fabs are increasingly scrutinizing system-level emissions, and chamber clean configurations that reduce CF4 generation through remote plasma retrofits are already demonstrating measurable reductions against earlier emission factors.
- Specialty gas supply volatility and input cost pressure. High-purity specialty gases essential to plasma etch processes continue to face supply chain friction in key regions, where limited domestic production amplifies price sensitivity. Helium, a critical gas used in plasma etching, has experienced price volatility with costs rising by more than fifty percent over the past two years. For equipment and flip-to-play service providers, this translates into procurement risk and margin pressure that must be managed through contract structures, yield optimization, and system efficiency improvements rather than simple pass-through pricing.
- Performance expectations at advanced nodes and packaging complexity. As feature sizes continue to shrink and 3D architectures proliferate, etch systems must deliver tighter control over profile, selectivity, and variability while maintaining throughput. Buyers are increasingly unwilling to accept trade-offs that slow cycle time or compromise yield; at the same time, they demand greater flexibility to handle diverse materials, including compound semiconductors and advanced packaging substrates. This pushes suppliers to balance deep specialization with adaptable platform architectures.
These challenges are not isolated headwinds; they are reshaping the basis of competition. Suppliers that treat regulatory compliance and gas efficiency as afterthoughts risk being penalized by procurement criteria and operating economics. Conversely, those that embed low-emission chamber designs, robust gas management, and predictable consumable strategies into their platforms are creating a more durable value proposition.
Forces Shaping the Next Phase of Growth
Several drivers are converging to determine how the market expands over the forecast period, and each carries distinct implications for product roadmaps, customer engagement, and capital allocation.
Technology innovation and system-level differentiation. The pace of advancement in plasma etch tools is increasingly defined by how well platforms integrate precision, repeatability, and process flexibility. Recent product introductions point toward a clear emphasis on single-wafer capability, high-temperature processing, and surface treatment enhancements that address both front-end patterning and back-end passivation or cleaning. One notable example is the introduction of a single-wafer Aqua Plasma system alongside a 700°C high-temperature PECVD system for etch applications, signaling a push toward platforms that can support demanding thermal profiles and advanced surface engineering in tighter footprint configurations. Exhibit showcases at industry events further reinforce this trajectory, as suppliers highlight etching and surface treatment advancements that map directly to next-generation device architectures.
For buyers, the implication is that best-in-class is no longer a single metric; it is a combination of etch uniformity, sidewall quality, temperature control, and compatibility with a growing library of materials. Suppliers that can demonstrate measurable improvements in these dimensions, while minimizing rework and consumable consumption, are better positioned to command premium positioning and longer replacement cycles.
Policy and regulatory dynamics as a design constraint and differentiator. Environmental regulation is evolving from a compliance checkbox into a design parameter. The mandated reduction targets for HFCs and associated gases compel equipment developers to reconsider how chamber cleans, gas delivery, and remote plasma configurations affect both process performance and emissions. Practical experience already shows that retrofitting chamber cleans to remote plasma systems can reduce CF4 generation by more than thirty-five percent, providing a tangible example of how system design choices translate into regulatory alignment and potential total cost advantages over the lifecycle of the tool.
Semiconductor Etch Equipment Market
This matters for strategy because it creates two reinforcing opportunities: first, differentiation through lower-emission, more efficient plasma architectures that reduce operating risk for fabs; second, value creation through service models that help customers sustain compliance while maintaining throughput. Companies that treat these mandates as innovation drivers rather than constraints can convert regulatory pressure into competitive advantage, especially in markets where environmental due diligence is increasingly integrated into procurement decisions.
Demand-side shifts across semiconductor and adjacent applications. The semiconductor segment continues to be the central engine of demand, fueled by advanced logic and memory roadmaps and the expansion of advanced packaging. At the same time, medical and microelectronics applications are building their own cases for plasma processing, where surface modification, cleanliness, and reproducibility directly affect product quality and regulatory conformance. Demand is also becoming more application-specific: rather than uniform growth across all uses, certain workflows require tailored etch chemistries, smaller lot sizes, or pilot-line flexibility before commitment to full production. This is reshaping how suppliers think about platform modularity, service responsiveness, and application engineering support.
Supply chain and cost structure recalibration. The volatility in specialty gases, combined with the need for high-purity inputs and reliable consumables, is prompting a broader reckoning with cost structures. Equipment buyers are increasingly focused on total cost of ownership rather than sticker price, weighing factors such as gas utilization efficiency, uptime, chamber life, service coverage, and the predictability of consumables spend. Suppliers are responding with a mix of engineering improvements and commercial flexibility, including refurbished and custom configurations, pilot-line and production-oriented variants, and partnerships that extend capabilities across the value chain.
One relevant development is the collaboration between a leading plasma etch provider and a quantum manufacturing initiative to enable scalable quantum manufacturing via plasma processes. This kind of partnership illustrates how demand can emerge from new application domains and how incumbents can extend relevance by aligning process expertise with frontier fabrication needs, rather than relying solely on incremental improvements within established segments.
Competitive Positioning and the Evolution of the Field
The competitive landscape is a mix of specialized suppliers, regional experts, and large-scale equipment manufacturers, each pursuing different strategies to win share and defend positioning.
Niche and mid-tier specialists are leveraging deep application knowledge, customized configurations, and flexible commercial terms to serve customers with narrower process requirements or pilot-line needs. One U.S.-based manufacturer focused on plasma cleaning, etching, stripping, ashing, and reactive ion etching systems for surface preparation and modification, including custom and refurbished models, exemplifies a strategy built on applicability breadth and optionality. Another provider delivering premium wafer-based plasma etch, deposition, and advanced packaging equipment for microelectronics manufacturing emphasizes high-quality, application-focused platforms that map to demanding production requirements. A U.K.-based supplier known for advanced plasma etch systems including silicon, dielectric, and compound semiconductor etching and dicing platforms has built a reputation around specialized process capability and platform families tailored to specific materials and workflows. A Japanese developer and manufacturer of deposition, etching, and surface treatment systems, including plasma-enhanced ALD and high-temperature PECVD tools, has leaned into process integration and thermal capability as a point of differentiation. A U.S. manufacturer of plasma etch, strip, and deposition systems for semiconductor applications, and a French provider of plasma etch and deposition equipment with a focus on pilot-line and production systems, both reflect strategies oriented toward practical deployment flexibility and customer-specific adaptation. A Korean supplier of plasma etching equipment for semiconductor fabrication processes adds a regional processing strength, while the recent demonstration focus on etching and surface treatment advancements further signals continued investment in showcasing process maturity.
On the other side of the field, major equipment manufacturers with plasma etch systems integrated into advanced node fabrication lines and global chip fabrication and advanced packaging portfolios bring scale, broad material coverage, and deep integration with overall manufacturing ecosystems. A global supplier with plasma etch systems for chip fabrication and advanced packaging, and a developer of dry etch systems for advanced logic and memory device fabrication, illustrate how scale players compete on breadth, roadmap alignment, and the ability to support high-volume manufacturing with consistent process control. A Japanese producer whose equipment is integrated into advanced node fabrication lines underscores the importance of alignment with leading-edge ramp scenarios and yield-critical processing.
The resulting competitive dynamics are evolving along several axes:
- Differentiation through application depth. Specialists are competing on process fit, customization, and responsive engineering for specific materials and workflows, which can be especially valuable in compound semiconductors, advanced packaging, and smaller-volume medical or microelectronics applications.
- Differentiation through scale and integration. Large players are competing on platform reliability, throughput, global service footprint, and the ability to address the most demanding high-volume logic and memory production environments.
- Commercial flexibility as a strategic lever. Refurbished and custom models, pilot-line configurations, and partnership-enabled expansions are increasingly used to broaden addressable demand and reduce barriers to adoption, particularly in cost-sensitive or emerging application segments.
- Ecosystem alignment and new application gateways. Collaborations aimed at scalable quantum manufacturing and other frontier domains indicate that incumbents are seeking growth vectors beyond traditional semiconductor etch, using process expertise to enter adjacent high-value fabrication domains.
Market concentration, as measured by leading competitor shares, remains moderate, reflecting a field where value is distributed across multiple capable suppliers rather than dominated by a single platform family. This is important because it means competitive outcomes will be determined less by raw scale alone and more by how effectively each supplier can match product, service, and commercial flexibility to customer needs across a widening set of applications and geographies.
Looking Ahead: Three Trends Shaping the 2026 to 2032 Horizon
Based on the interplay of technology roadmaps, regulatory trajectories, and cost dynamics, several forward-looking trends are likely to define the next phase of market development.
Trend one: process efficiency and emissions control become core purchasing criteria. As regulatory reduction pathways tighten and input costs remain sensitive, buyers will increasingly evaluate plasma etch platforms on lifecycle emissions, gas utilization, chamber clean efficiency, and serviceability, alongside traditional metrics of profile quality and throughput. Systems that demonstrably lower emissions, reduce specialty gas dependence, and simplify compliance maintenance will gain traction, particularly in regions with strict environmental frameworks and in fabs managing multiple process gases across demanding schedules. The commercial opportunity here is twofold: for suppliers, it opens the door to design-led differentiation and value-added service packages; for buyers, it can translate into lower operating risk and more predictable long-term economics.
Trend two: platform modularity and application breadth will determine addressable demand. The widening range of applications, from advanced node patterning to compound semiconductors, advanced packaging, medical devices, and emerging fabrication domains, rewards suppliers that can offer adaptable architectures without abandoning process quality. Flexibility in configuration, the availability of pilot-line and production variants, and the ability to provide custom or refurbished options will become important enablers of market entry and expansion. Suppliers that combine a credible core process capability with a modular approach to add-ons, chamber options, and service modules are better positioned to capture demand from customers who need to de-risk scaling before committing to full production systems.
Trend three: partnerships and ecosystem extensions will create new growth vectors. The emergence of collaborations focused on scalable quantum manufacturing and other frontier processing needs suggests that plasma etch expertise is increasingly relevant beyond the traditional semiconductor core. For established players, partnerships can extend reach into high-value domains that demand specialized plasma control, while for suppliers with deep application knowledge, alignment with new fabrication initiatives can open routes to participate in next-generation technology scaling. This trend carries the potential for incremental revenue growth and brand reinforcement, but it also introduces execution risk: new applications require rapid learning, rigorous process validation, and close alignment with customer roadmaps that may still be evolving.
These trends imply both opportunity and uncertainty. On the upside, demand for higher-performance, lower-emission, and more flexible plasma etch systems is broad-based and likely to persist as technology nodes advance and new application sets mature. On the downside, policy implementation pace, gas supply conditions, and the timing of technology ramps can shift the rate of adoption. Buyers and suppliers alike should therefore plan for a market that is growing strongly over the horizon but where the timing and mix of demand are sensitive to external factors beyond any single company's control.
Strategic Actions for Executives, Investors, and Procurement Teams
For manufacturers and equipment suppliers, the priority is to convert regulatory and cost pressures into design and service advantages. This means continuing to invest in chamber and gas management architectures that reduce emissions and improve consumable efficiency, while building flexible product lines that span pilot-line, production, custom, and refurbished configurations. Equally important is service and application engineering: customers will increasingly choose platforms based on predictable uptime, compliance support, and the ability to adapt processes to new materials and workflows. Suppliers that align their commercial models with total cost of ownership, rather than unit price alone, will be better placed to defend margins and extend replacement cycles.
For investors, the key is to differentiate between cyclical demand and structural tailwinds. The broader market trajectory remains robust, but the distribution of value will likely skew toward suppliers that demonstrate process differentiation, regulatory alignment, and commercial agility across multiple applications and regions. Attention should be paid to signs of successful entry into adjacent application domains, evidence of emissions-reducing platform features, and the ability to manage specialty gas exposure through engineering and contractual mechanisms. Portfolio positioning should account for both the strong headline growth and the possibility that regional and application-level demand will shift at different rates.
For procurement and operations leaders evaluating plasma etch systems, the focus should broaden from specification sheets to lifecycle economics and risk management. Evaluate platforms for gas utilization efficiency, emissions profile, chamber clean strategy, service coverage, and the supplier's ability to support custom or pilot requirements without sacrificing process quality. Where feasible, structure engagements to test performance under real production conditions, and negotiate terms that align consumable and service costs with actual usage patterns. In an environment where input volatility and regulatory requirements are not going away, the most resilient buying decisions are those that balance performance with long-term operating predictability.
The strategic stakes in this market are rising as growth continues but the basis of competition becomes more demanding. Decision-makers who pair a clear understanding of the regulatory and cost environment with rigorous evaluation of process fit, flexibility, and supplier capabilities will be best positioned to extract value as the market moves toward 2032. For those seeking fully segmented data, regional and application-level detail, and customized recommendations aligned to specific investment or operational objectives, a comprehensive research report can provide the deeper granularity needed to inform precise decisions.
PW Consulting
For detailed analysis of this topic, please visit the official page: Plasma Etch System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vacuum Suction Cups Market: How 6.5% CAGR and 253.5M Scale Redefine Growth
By pmarketresearch, 2026-09-21
Vacuum Suction Cups Market: Strategic Trends and Business Opportunities in Automation-Driven Handling
The global vacuum suction cups market has entered a phase of steady, technology-led expansion, underpinned by consistent compound annual growth of 6.5 percent between 2020 and 2032. After a baseline period shaped by industrial recalibration and supply chain adjustments, revenue growth accelerated through the mid-2020s as automation adoption matured across discrete and process manufacturing. The market trajectory reflects a structural shift rather than a cyclical recovery: vacuum handling is increasingly integrated into core production workflows, with demand concentrated in high-throughput environments where precision, repeatability, and material compatibility are non-negotiable. This expansion is not evenly distributed across applications or materials. Instead, it is shaped by the intersection of product design innovation, regulatory expectations, and regional manufacturing priorities, creating a landscape where differentiation depends on how well suppliers align with application-specific requirements.
Beneath this growth narrative, several structural challenges define the current inflection point. First, performance expectations are rising faster than standardization, forcing suppliers to respond to highly variable surface conditions, material sensitivities, and cycle-time demands without sacrificing reliability. Second, compliance and hygiene requirements are becoming embedded in procurement decisions, particularly in food, packaging, and electronics handling, where material certification and process validation carry increasing weight. Third, the supply base is expanding in capability and geography, which intensifies competition on price and lead times while simultaneously raising the bar for technical support, customization, and integration services. These dynamics mean that market success is increasingly determined by application expertise, material science, and the ability to deliver repeatable performance in demanding environments.
Key Drivers Shaping Market Direction
Technology Innovation and Material-Specific Performance
Innovation in suction cup design and material composition is one of the most influential drivers of demand segmentation. Buyers are moving beyond generic handling components toward solutions engineered for specific substrates, surface textures, and process conditions. This is especially visible in electronics, precision assembly, and sheet handling, where mark-free contact, controlled pressure distribution, and static discharge protection are becoming baseline expectations. The expansion of specialized product families—such as ESD-focused designs for sensitive components and single-lip configurations for heavy flat objects—reflects a broader industry shift toward application-tailored handling rather than universal parts.
Worldwide Cupping Therapy Kits Market
Material selection is also shaping adoption patterns. Suction cups manufactured from silicone and nitrile-based compounds account for a substantial share of production, with silicone-based models representing a significant portion of domestic demand. Bellows-style designs remain widely used for uneven surface handling, highlighting the continued importance of geometry in achieving reliable grip across variable contours. At the same time, material grades that satisfy hygiene and process standards are gaining prominence in packaging environments, where cleanliness and compliance directly influence line design choices.
Regulatory and Hygiene Standards as Purchasing Filters
Regulatory expectations and food-safety standards have become practical filters in procurement, particularly in automated packaging lines. FDA-compliant, food-grade suction cups are no longer treated as niche accessories; they are increasingly specified where hygienic handling is essential. In meat and dairy packaging, a meaningful share of automated lines now relies on suction cups made from compliant materials, reflecting the growing importance of contamination control, cleanability, and material traceability. In packaging operations more broadly, compliance-oriented suction solutions contribute to a notable portion of consumption where hygiene requirements shape equipment specification.
This regulatory influence does more than expand a product category; it changes the buying process. Procurement teams increasingly evaluate material certifications, chemical compatibility, clean-in-place compatibility, and documentation alongside mechanical performance. Suppliers that can provide verified material compliance and application guidance gain an advantage in environments where downtime, audit risk, and line validation are costly.
Demand-Side Shifts in Automation and Line Throughput
Demand is being reshaped by the expansion of automated pick-and-place, transfer, and assembly operations across multiple sectors. Automotive assembly remains a significant application anchor, but the market is increasingly diversified by woodworking and furniture production, general industrial handling, and specialized material transfer. Two forces are especially important. The first is the push for faster cycle times with less manual intervention, which increases the share of handling tasks assigned to vacuum-based systems. The second is the need for gentler, more consistent handling of fragile or sensitive materials, which favors purpose-built geometries and material grades over generic components.
These demand-side changes are also changing how end users evaluate performance. Reliability across shift patterns, ease of integration with existing vacuum systems, and consistency across production batches are becoming as important as unit cost. As a result, buyers are increasingly willing to differentiate by specification when the application justifies it, rather than defaulting to the lowest-priced option.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures in this market are influenced by raw material availability, manufacturing precision, and the level of customization required. While commodity-style components remain price-sensitive, higher-specification solutions—especially those involving specialized materials, smaller diameters for delicate handling, or certifications for regulated environments—command different value logic. This creates a two-tier competitive environment: one shaped by volume and cost efficiency, and another shaped by technical value, integration support, and application reliability.
At the same time, suppliers are responding to lead-time and service expectations by expanding configurable options, standardizing core families, and reserving customization for cases where performance or compliance demands it. This approach helps balance flexibility with manufacturing efficiency, an important consideration in markets where demand is broad but application requirements vary sharply.
Competitive Landscape and Leading Strategies
Strategic Positioning Across the Supply Base
The competitive field includes established European and North American manufacturers, Asian suppliers with expanding configuration options, and automation-focused providers that emphasize modular integration. Leadership in this market is not defined solely by scale; it is increasingly defined by how clearly a company positions itself against application needs. Some manufacturers compete through broad reference libraries and highly configurable product ranges, enabling them to serve diverse industrial handling requirements. Others compete through specialization, such as ESD protection for electronics, food-grade compliance for packaging, or geometries designed for heavy flat objects and demanding surfaces.
This differentiation matters because buyers often evaluate suction cups not as standalone parts but as part of a handling solution. Companies that offer clear material categorization, application-specific series, and integration-friendly designs are better positioned to capture demand in environments where handling consistency and process compatibility determine purchasing decisions.
Recent Product Activity as a Signal of Direction
Recent product activity highlights where innovation is concentrated. In early to mid-2026, several suppliers introduced or expanded lines intended for sensitive handling, surface complexity, and heavy flat objects. One notable development was the introduction of an ESD-focused suction cup material designed for sensitive electronics handling, with emphasis on minimized marking and maximized static protection. This aligns with demand in battery, fuel cell, and electronic component handling, where surface integrity and electrostatic control are critical.
At the same time, a major supplier expanded its mini ESD suction cup range with smaller diameters aimed at battery, fuel cell, and electronic components, while also launching new families for demanding surface handling and single-lip designs for flat heavy objects such as glass and sheet metal. These moves indicate a dual trajectory: one toward finer handling of sensitive components, and another toward robust handling of large or irregular surfaces. The pattern suggests that product strategy is becoming more application-specific, with material and geometry treated as enablers of performance rather than interchangeable specifications.
Market Structure and Evolutionary Trends
The market remains moderately concentrated, with the largest players holding a meaningful but not dominant share of total revenue. This structure creates room for both differentiation and selective consolidation. Larger suppliers benefit from broader portfolios, integration capabilities, and established distribution relationships, while smaller or regionally focused manufacturers can compete through specialization, responsiveness, and niche application expertise.
Bra Cups Market
Looking ahead, the competitive landscape is likely to evolve along three paths. First, differentiation will increasingly depend on material certification, ESD and hygiene capabilities, and application documentation, especially in regulated or high-value handling environments. Second, integration and modularity will become more important as buyers seek components that fit cleanly into automated systems and simplify changeover. Third, regional supply dynamics will continue to shape competition, with buyers weighing local support, lead times, and configuration flexibility against price. New entrants may find opportunities in specialized materials, smaller-component handling, or regional service models, while incumbents will need to keep expanding application coverage without diluting manufacturing efficiency.
Future Trends and Commercial Opportunities
Trend One: Application-Tailored Solutions Will Outperform Generic Components
Over the next three to five years, demand is likely to shift further toward suction cups designed for specific materials, surface conditions, and compliance contexts. Generic handling components will continue to serve cost-sensitive or lower-specification applications, but higher-value demand will favor solutions that reduce mark formation, improve grip on variable surfaces, and meet electrostatic or hygiene requirements. For suppliers, this creates an opportunity to build value around application series, material grades, and configuration support rather than competing solely on volume pricing.
Trend Two: Regulated and Sensitive Handling Will Expand as a Strategic Segment
Food-grade, ESD-safe, and otherwise compliance-oriented suction solutions are expected to remain important growth vectors, particularly where automated lines must satisfy hygiene, safety, or component-integrity standards. This trend favors manufacturers that can provide verified materials, clear certification pathways, and application guidance. It also increases the strategic importance of technical sales and integration support, since specification choices often depend on line design, cleaning protocols, and handling risk.
Trend Three: Integration and Modularity Will Redefine Supplier Value
As handling systems become more tightly integrated into automated workflows, buyers will increasingly evaluate suction cups alongside connectors, mounting options, vacuum circuit compatibility, and changeover efficiency. Suppliers that design for modular integration and offer consistent families across sizes and materials can reduce engineering friction and improve total cost of ownership perceptions. The commercial opportunity lies in shifting from component sales to solution enablement, where performance, compatibility, and documentation collectively justify specification choices.
These trends carry risks. Demand may fragment across more application categories, raising complexity for manufacturers that over-standardize. Regulatory expectations may continue to evolve, requiring ongoing material validation and documentation. In addition, regional cost pressures and expanding supplier options may intensify price competition in commoditized segments, squeezing margins for players that lack application differentiation or service depth.
Strategic Actions for Decision-Makers
For Manufacturers and Product Leaders
Focus product roadmaps on application differentiation rather than broad catalog expansion alone. Prioritize material grades and geometries that address high-value handling needs, including ESD-sensitive components, heavy flat surfaces, and hygienic packaging environments. Balance configurable standard families with targeted customization to preserve manufacturing efficiency while meeting specialized demand. Equally important, strengthen application documentation and technical support so specification decisions are easier to justify inside end-user engineering and procurement processes.
For Investors and Corporate Development Teams
Evaluate opportunities based on application specificity, certification readiness, and integration capability rather than volume alone. Companies with strong positions in sensitive handling, food-grade compliance, or demanding surface applications may offer more resilient value propositions than those competing primarily on price in commoditized segments. Watch for consolidation patterns among suppliers with complementary portfolios, especially where product breadth, regional support, or material expertise can be combined to serve broader handling requirements.
For Procurement and Operations Teams
Treat specification as a risk and performance decision, not just a cost decision. Where handling involves sensitive surfaces, food contact, or high variability, prioritize material certification, mark-free performance, and compatibility with existing vacuum infrastructure. Standardize where possible to reduce changeover complexity, but preserve the ability to specify application-specific designs when process requirements justify them. Build internal evaluation criteria that include cleanability, compliance documentation, and integration fit alongside mechanical performance and unit price.
For organizations seeking a more granular view of market size by segment, regional dynamics, material and application splits, and company-level positioning, a full market research report can provide the detailed data and custom perspective needed for planning. Detailed breakdowns, scenario-based sizing, and supplier benchmarking can help translate the strategic themes outlined here into procurement decisions, product priorities, and investment theses aligned with specific operational goals.
For detailed analysis of this topic, please visit the official page: Vacuum Suction Cups Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Confused about where to play Togel Online safely? You’re not alone. With so many sites claiming to be reliable, finding a legitimate platform that protects your funds, respects payouts, and offers fair play can be daunting. ALEXISTOGEL stands out by combining robust security, transparent operations, and an official PAGCOR license valid through 2026 — giving you peace of mind from sign-up to jackpot.

Why choose ALEXISTOGEL for Togel Online?
Choosing an operator for Togel Online is about trust, speed, and clarity. ALEXISTOGEL meets these criteria with several clear advantages:
Official licensing and regulation
Legitimacy matters. ALEXISTOGEL operates under a PAGCOR license (valid 2026), ensuring regulatory oversight, compliance with responsible gaming standards, and verified financial procedures. Licensing helps protect players and confirms that the operator meets industry requirements.
Secure transactions and data protection
Security is non-negotiable. ALEXISTOGEL uses industry-standard encryption for deposits, withdrawals, and account data. Multiple payment options, quick processing, and transparent transaction records mean you can play with confidence, knowing your funds and personal information are handled safely.
Guaranteed payouts and customer-first policies
Reputation is built on delivery. ALEXISTOGEL emphasizes prompt jackpot payouts and customer support that responds quickly to queries. Clear terms and reliable dispute resolution put players first, so winners receive their prizes without unnecessary delays.
How to get started — a simple Togel Online guide
Getting into Togel Online at ALEXISTOGEL is straightforward, even for beginners:
1. Register and verify
Create an account with basic details and follow KYC steps to verify identity. Verification speeds up future withdrawals and ensures account security.
2. Deposit safely
Choose from multiple secure payment methods. ALEXISTOGEL supports trusted gateways and provides clear fees and processing times so you can manage your bankroll without surprises.
3. Pick your numbers and bet type
Togel offers various bet formats — from 2D/3D to full-number combos and pari-mutuel styles. Start small to learn the dynamics, then scale your bets when you’re comfortable.
4. Check draws and claim winnings
Results are published promptly after each draw. If you win, ALEXISTOGEL’s payout process is designed to be fast and transparent — winners are notified and paid per the platform’s terms.
Smart tips for playing responsibly
Togel can be exciting, but professional players treat it as entertainment rather than guaranteed income. Follow these guidelines to play responsibly:
- Set a budget and stick to it: Define a session limit and avoid chasing losses.
- Use promotions wisely: Bonuses can boost playtime but read wagering requirements carefully.
- Keep records: Track your bets and results to spot patterns and manage spending.
- Take breaks: Regular breaks reduce impulsive decisions and keep gameplay enjoyable.
Features that make ALEXISTOGEL stand out
ALEXISTOGEL is built around player needs. Key features include:
- Transparent odds and clear bet terms
- Responsive multilingual support
- Fast withdrawal processing for verified players
- Secure mobile and desktop platforms for on-the-go play
- Regular promotions and loyalty rewards for active members
Frequently asked questions (FAQ)
Is ALEXISTOGEL safe for Togel Online?
Yes. The PAGCOR license and encryption measures ensure compliance and security. Always complete verification and use recommended payment channels.
How quickly are jackpot payouts processed?
Payout speed depends on verification status and payment method. Verified accounts typically receive funds within the timeframe specified in the platform’s payout policy.
Can I play on mobile?
Yes. ALEXISTOGEL supports mobile-friendly interfaces and dedicated apps where available, enabling secure play from smartphones and tablets.
Final thoughts — play smart, play safe
Finding a trustworthy Togel Online platform doesn’t have to be stressful. ALEXISTOGEL’s PAGCOR license for 2026, secure transaction systems, and commitment to prompt payouts make it a compelling choice for both new and experienced players. Remember to play responsibly, take advantage of verified promotions, and verify your account early to enjoy fast, reliable payouts when luck is on your side. Ready to play confidently? Visit ALEXISTOGEL to get started and experience a safer, more transparent Togel Online journey.
Finding a reliable online Toto Togel platform can be daunting. With so many options, players need a site that combines strong security, transparent rules, dependable payouts and professional support. ALEXISTOGEL positions itself as a trusted partner for players seeking a safe, regulated experience—backed by a PAGCOR license valid through 2026. This article explains why smart players choose regulated platforms, how ALEXISTOGEL addresses common concerns, and practical tips to maximize enjoyment while minimizing risk.

Why Regulation and Licensing Matter
Legal licensing is the primary signal that a gaming operator follows industry standards. A PAGCOR license indicates that a site is subject to oversight, auditing and compliance requirements. For players, that means:
- Fair play: Random number generation and game fairness are monitored.
- Financial safeguards: Player deposits and withdrawals are handled under regulated procedures to reduce fraud risk.
- Accountability: Licensed operators must address disputes and adhere to payout commitments.
ALEXISTOGEL’s PAGCOR license for 2026 is a central trust indicator—especially for players who prioritize secure transactions and guaranteed jackpot (JP) payouts.
What Sets ALEXISTOGEL Apart
ALEXISTOGEL combines regulatory credibility with practical features that matter to both beginners and experienced Toto Togel players:
1. Verified Licensing and Compliance
Operating under a recognized PAGCOR license through 2026, ALEXISTOGEL commits to transparent conduct. Regulatory oversight reduces operational risk and enforces standards for dispute resolution and payout fulfillment.
2. Secure Transactions and Data Protection
Top-tier encryption, secure payment gateways and privacy protections are standard. These measures protect personal data and financial information, helping players focus on the game rather than security worries.
3. Responsive Customer Consultation
A key offering is personalized consultation for newcomers and high-stakes players alike. Whether you need help understanding bet types, managing your bankroll or initiating a withdrawal, professional support guides each step.
4. Reliable Jackpot Payouts
ALEXISTOGEL emphasizes a simple promise: "Play safe, JP is guaranteed to be paid." Transparent terms and a clear payout process reduce uncertainty when big wins occur.
How to Start Playing Toto Togel on ALEXISTOGEL
Follow these practical steps to get started safely:
- Create and verify your account: Complete identity verification to unlock full access and faster withdrawals.
- Review rules and odds: Understand the specific Toto Togel formats available and the payout structures.
- Deposit via secure channels: Use supported payment methods and inspect fee and processing time details.
- Place small test bets: Begin with conservative stakes to confirm the platform’s responsiveness and withdrawal procedures.
- Request a withdrawal: Confirm the speed and reliability of the payout process with a small cash-out first.
Responsible Play: Bankroll and Risk Management
Even on trustworthy platforms, responsible play is essential. Tips for sustainable Toto Togel enjoyment:
- Set a budget: Allocate only what you can afford to lose and track your spending.
- Use limits: Employ deposit, loss and session limits where available.
- Avoid chasing losses: Treat losses as part of the game rather than a problem to fix by escalating stakes.
- Take breaks: Regular pauses help maintain perspective and prevent impulsive decisions.
FAQ: Common Questions about Toto Togel and ALEXISTOGEL
Is ALEXISTOGEL safe?
Yes. The PAGCOR 2026 license, secure payment systems and professional support combine to make ALEXISTOGEL a safe and reliable choice for Toto Togel players.
Are jackpot payouts guaranteed?
ALEXISTOGEL advertises guaranteed JP payouts under clearly stated terms. Always review the terms and conditions so you understand processing times and verification steps required for large withdrawals.
Can I get help if I’m new to Toto Togel?
Absolutely. ALEXISTOGEL provides consultation services to help newcomers learn betting formats, odds interpretation and bankroll strategies.
Conclusion: Play Smart with a Trusted Partner
Toto Togel is more enjoyable and sustainable when played on a regulated, transparent platform. ALEXISTOGEL’s PAGCOR 2026 license, secure systems, customer consultation and commitment to guaranteed jackpot payouts make it a compelling option for players seeking safety and professionalism. If you want a site that prioritizes fair play, dependable payouts and clear support, ALEXISTOGEL deserves consideration—play responsibly and verify all account and withdrawal procedures to ensure a smooth, secure experience. Ready to play with confidence? Visit ALEXISTOGEL to learn more about their services, licensing details and how to get started.